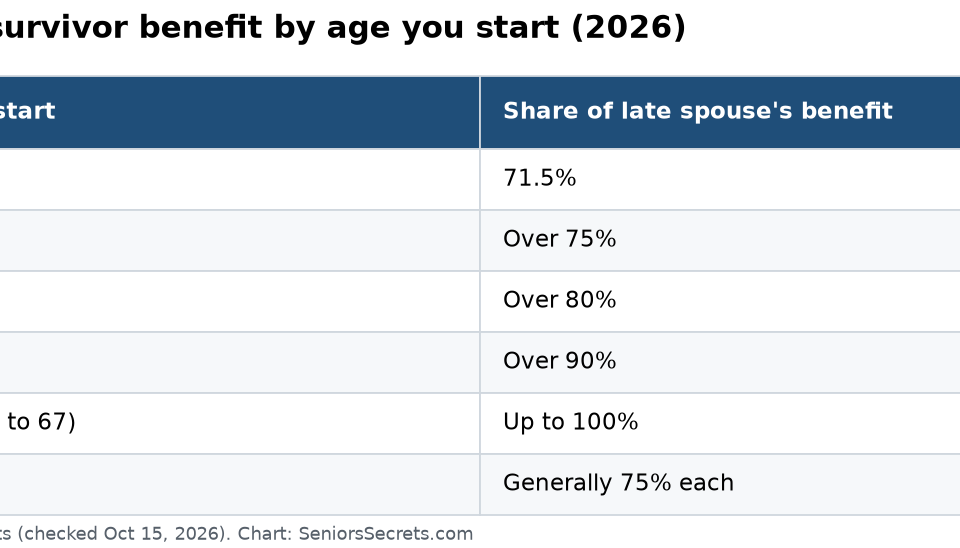
Social Security Survivor Benefits 2026: What Widows and Widowers Get, and the 2027 Raise

A widow or widower can get 71.5% of the late spouse’s Social Security benefit at age 60, rising to 100% at full retirement age (66 to 67). The average aged widow or widower gets about $1,936 a month now. With the 3.6% raise announced on October 14, 2026, that rises to about $2,005 in January 2027.
Losing a spouse brings a pile of paperwork at the worst time. Survivor benefits are one of the few pieces that can truly help your budget, so it pays to understand them before you call. This guide uses Social Security’s own pages on who can get survivor benefits and what you could get, plus the 2027 COLA fact sheet, all checked on October 15, 2026.
I research Social Security rules for readers. I am not a financial planner or an SSA employee.
Who qualifies
Widows and widowers may qualify if they:
- Are age 60 or older, or 50 to 59 with a disability, and
- Were married for at least 9 months before the death, and
- Did not remarry before age 60 (or 50 if disabled).
Divorced spouses can qualify too if the marriage lasted at least 10 years. You may also qualify at any age, and no matter how long you were married, if you are caring for the child of the person who died.
Children can get benefits if they are unmarried and under 18, or 18 to 19 and still in high school full time, or any age with a disability that began before 22. Dependent parents age 62 or older who relied on the child who died may also qualify.
How much you get at each age
Social Security says payments start at 71.5% of your late spouse’s benefit and rise the longer you wait.
| Your age when you start | Share of your late spouse’s benefit |
|---|---|
| 60 | 71.5% |
| 61 | Over 75% |
| 63 | Over 80% |
| 65 | Over 90% |
| Full retirement age (66 to 67) | Up to 100% |
| Child of the worker | Generally 75% each |
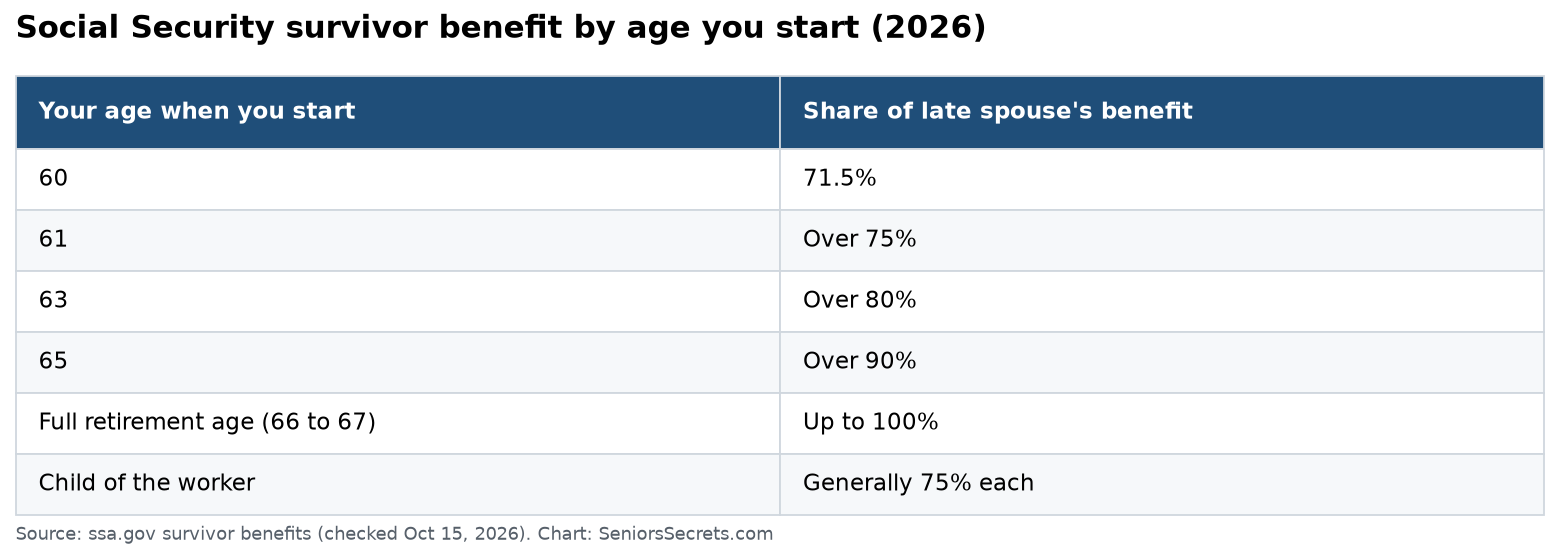
One family can only get so much. A family maximum caps the total paid on one worker’s record, so each person’s share may be cut when several people claim. Ex-spouses do not count toward that cap.
There is also a one-time $255 death payment for a surviving spouse or certain minor children.
If your spouse claimed early or late
The 100% figure is based on what your spouse was actually receiving, or was due, at death. Two rules matter:
- Spouse claimed early. Your benefit at full retirement age is limited to the larger of what your spouse got or 82.5% of their full benefit. Waiting past full retirement age does not raise it further.
- Spouse waited past full retirement age. Delayed retirement credits they earned carry over to you, so your benefit can be larger than their full benefit.
This is why two widows with similar late husbands can get very different checks.
The 2027 raise and average checks
On October 14, 2026, Social Security announced a 3.6% cost-of-living adjustment for 2027. It starts with January 2027 payments.
| Who | Average before raise | Average from January 2027 |
|---|---|---|
| Aged widow or widower alone | $1,936 | $2,005 |
| Widowed mother and two children | $3,932 | $4,074 |
| All retired workers | $2,095 | $2,170 |
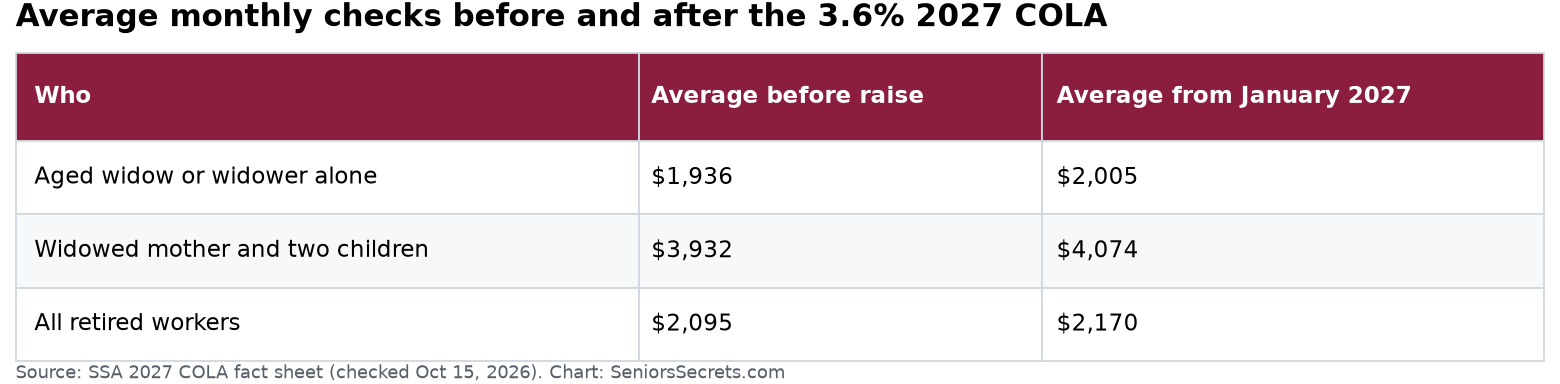
Your own amount depends on your spouse’s earnings record and your age when you start. Online, your COLA notice shows up in your my Social Security account in late November. Paper notices go out in December. Our my Social Security account guide shows how to set it up.
Survivor benefits vs your own retirement benefit
If you qualify for both, Social Security pays the higher one. They are not added together. But you can switch later. SSA gives this example: take survivor benefits first, then switch to your own retirement benefit at 70 when it is at its highest.
This switch is one of the most valuable moves for widows. Two common plans:
- Your own benefit is smaller. Start your own reduced retirement benefit at 62. Switch to the full survivor benefit at your full retirement age.
- Your own benefit is larger. Take the survivor benefit early. Let your own benefit grow until 70, then switch.
Ask the SSA agent to run both plans with your real numbers. Write down the name of the person you spoke with and the date.
Working while you collect
If you are under full retirement age and still work, an earnings limit applies. For 2026, Social Security holds back $1 for every $2 you earn above $24,480. In 2027 that limit rises to $25,560. In the year you reach full retirement age, the limits are higher ($65,160 in 2026 and $67,920 in 2027), and $1 is held back for every $3. Once you reach full retirement age, there is no limit. Our guide to working after retirement explains how withheld money comes back later.
Remarriage and government pensions
- Remarrying at 60 or later does not end your survivor benefit.
- Remarrying before 60 usually does, unless that later marriage ends.
- If you get a government pension from work not covered by Social Security, the Social Security Fairness Act ended the old offset rules. Read our Social Security Fairness Act guide for what changed.
How to apply
You cannot apply for survivor benefits online. Call 1-800-772-1213 (TTY 1-800-325-0778), Monday to Friday, 8 a.m. to 7 p.m., or visit a local office. Funeral homes usually report the death, so you may not need to.
Have these ready:
- Your spouse’s Social Security number (or birth date and parents’ names)
- Death certificate
- Marriage certificate (and divorce papers if you are a former spouse)
- Your bank details for direct deposit
- Recent W-2s or tax returns for you and your spouse
Apply soon. Some survivor benefits can be paid back only a limited time, so waiting can cost you months. See our guide to retroactive Social Security benefits.
Common questions
How much will a widow get from Social Security in 2027?
It depends on your spouse’s record and your age. The average aged widow or widower alone gets about $2,005 a month after the 3.6% raise in January 2027.
Can I get survivor benefits at 60?
Yes. You can start at 60, or at 50 if you have a disability. At 60 you get 71.5% of your late spouse’s benefit.
Can I get my own retirement and survivor benefits together?
No. Social Security pays the higher one. You can start one and switch to the other later.
Does remarrying stop survivor benefits?
Not if you remarry at 60 or older. Remarrying before 60 usually ends them.
Can I apply for survivor benefits online?
No. Call 1-800-772-1213 or visit a Social Security office.
Written by Khasim Basha Shaik. I research Social Security and Medicare rules for readers. I am not a financial planner, attorney or SSA employee. This article summarizes ssa.gov materials and is not personal financial advice. Last reviewed October 15, 2026.
Related guides

The $6,000 Senior Tax Deduction for 2025 to 2028: Who Qualifies and How to Claim It
2027 Social Security COLA Is 3.6%: What It Means for Your Check, SSI and Medicare
The $90 Medicare Part B Rebate: Who Gets It, When It Arrives, and What to Watch For