Working While Collecting Social Security in 2026: The Earnings Test, Worked Examples and What Happens at Full Retirement Age

You can work and collect Social Security at the same time. But if you’re younger than full retirement age, Social Security’s retirement earnings test may hold back some of your benefit once your earnings pass a set limit. In 2026, that limit is $24,480 a year. In the year you reach full retirement age, it rises to $65,160, and once you hit full retirement age the limit disappears.
The part most people miss: withheld benefits aren’t gone. When you reach full retirement age, Social Security recalculates your monthly check to credit the months it held back.
I’m a researcher, not a financial planner or tax professional. The figures below come from the Social Security Administration’s actuarial tables and its publication How Work Affects Your Benefits. Check your own numbers with SSA before making a decision.
The 2026 earnings limits
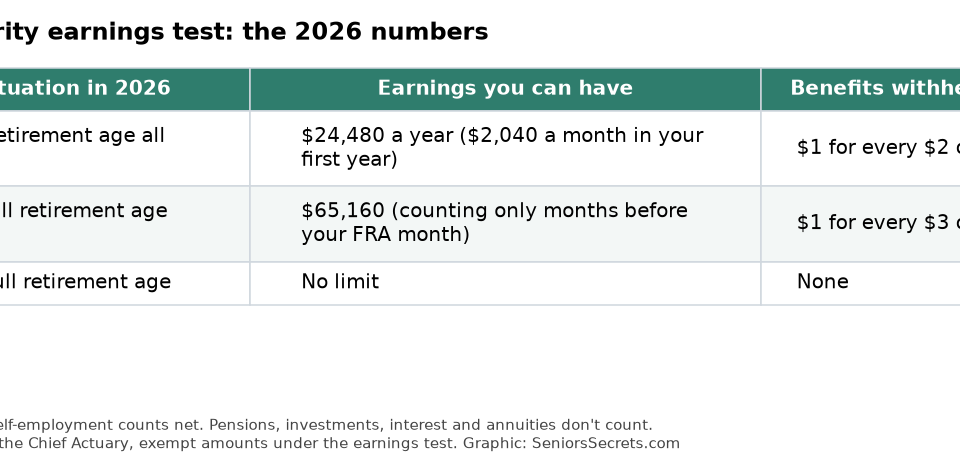
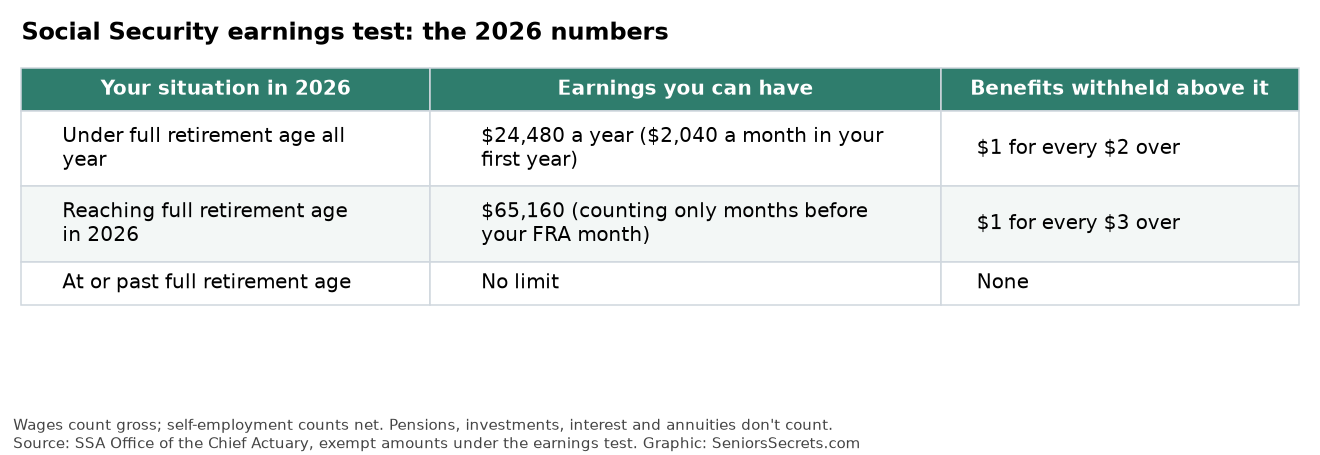
Social Security uses two limits, depending on how close you are to full retirement age (FRA). These are the official 2026 exempt amounts from SSA’s Office of the Chief Actuary:
| Your situation | 2026 limit | What’s withheld |
|---|---|---|
| Under FRA for all of 2026 | $24,480 | $1 for every $2 above the limit |
| Reaching FRA during 2026 | $65,160 (earnings before your FRA month only) | $1 for every $3 above the limit |
| At or past FRA | No limit | Nothing |
The limits rise most years with average wages. In 2025 they were $23,400 and $62,160.
For anyone born in 1960 or later, full retirement age is 67. My guide to full retirement age covers the schedule for earlier birth years.
What counts as earnings, and what doesn’t
The earnings test only looks at money you earn from work:
- Wages: your gross pay before deductions, including bonuses, commissions and vacation pay. Pre-tax retirement contributions from your paycheck still count.
- Self-employment: your net earnings after business expenses.
It ignores income that doesn’t come from current work:
- Pensions, including government and military pensions
- Investment income, interest, dividends and capital gains
- Annuities and IRA or 401(k) withdrawals
- Other government benefits, veterans’ benefits and jury duty pay
- Rental income, unless you run rentals as a business
So a retiree who draws $50,000 a year from a 401(k) and earns nothing from work isn’t affected by the earnings test at all.
Worked example 1: under full retirement age all year
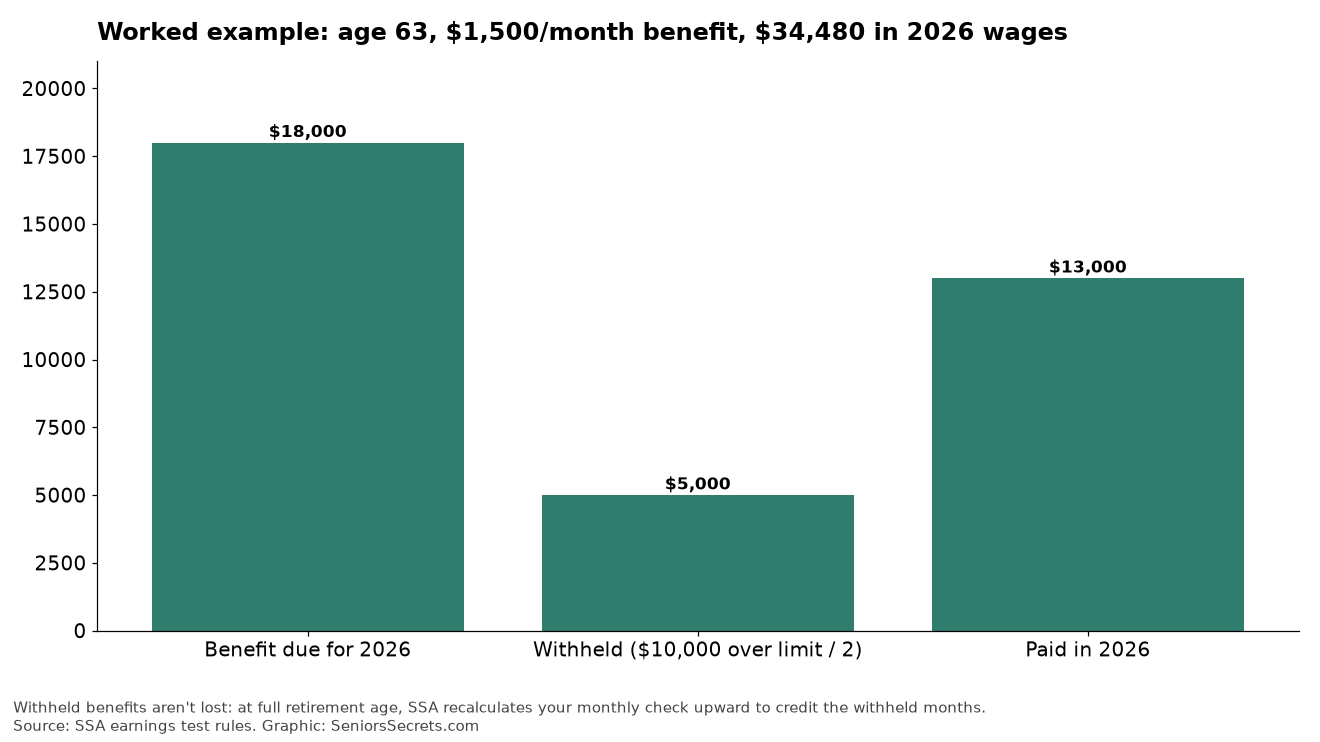
Linda is 63 in 2026. Her Social Security benefit is $1,500 a month, or $18,000 for the year. She works part-time and earns $34,480.
- Earnings over the limit: $34,480 − $24,480 = $10,000
- Withheld: $10,000 ÷ 2 = $5,000
- Paid to Linda in 2026: $18,000 − $5,000 = $13,000
Social Security doesn’t trim each check by a small amount. It usually withholds whole monthly payments at the start of the year until it has held back enough. Linda’s January through April checks ($6,000) would be withheld, and she’d get her full $1,500 from May onward. The extra $1,000 is paid back after the year ends, once her actual earnings are known.
Worked example 2: the year you reach full retirement age
Robert turns 67 in October 2026. Only his earnings from January through September count, and the higher $65,160 limit applies. He earns $75,160 in those nine months.
- Over the limit: $75,160 − $65,160 = $10,000
- Withheld: $10,000 ÷ 3 = $3,333
What he earns from October on doesn’t matter. From that month forward, he can earn any amount with no withholding.
Worked example 3: the first-year monthly rule
Your first year of retirement gets a special rule that helps people who retire partway through a year. In that year, Social Security can pay you a full benefit for any “non-service” month. That’s a month when your earnings are $2,040 or less (in 2026) and you’re under FRA all year, no matter how much you earned before you retired.
Say Maria retires in June 2026 at 64 after earning $60,000 since January. She then takes a part-time job paying $1,500 a month. Her annual earnings are far above $24,480, but each month from July on is under $2,040. So she can get her full benefit for those months.
For self-employed people, a month also counts as non-service only if you work 45 hours or less in your business. That cutoff can be lower for some highly skilled work.
Why withheld benefits come back at full retirement age
This is the part that changes the math. At full retirement age, SSA recalculates your benefit as if you’d claimed later, leaving out every month it withheld.
Here’s how that works for someone with an FRA of 67 who claims at 62:
- Claiming at 62 cuts the benefit by 30%.
- Suppose the earnings test withholds 12 full months of benefits over the following years.
- At 67, SSA treats the claim as if it started at 63. That’s a 25% reduction instead of 30%, and it’s permanent.
That higher check continues for life, so the withheld money comes back gradually. It doesn’t come back as a lump sum. If you live into your 80s, you’ll usually recover it and more.
Does working raise your Social Security benefit?
It can. SSA bases your benefit on your 35 highest-earning years, adjusted for wage growth. Each year SSA automatically reviews your new earnings. If a year of work while collecting beats one of your lower years, your benefit goes up, usually starting the following January.
This helps most if you have years with zero or low earnings, like time out of the workforce. It also takes $1,890 in 2026 earnings to earn one Social Security credit, which matters if you’re still short of the 40 credits needed for retirement benefits.
You’ll still pay Social Security and Medicare payroll taxes on your wages, even while you’re collecting.
How working affects your family’s benefits
If your spouse, or a child, gets benefits on your record and you’re under FRA, your excess earnings can reduce the whole family’s benefits on your record, not just yours. Your spouse’s own earnings, though, only affect your spouse’s benefit. My guide to spousal benefits explains how those payments are figured.
Taxes: the other way work affects your benefits
The earnings test isn’t a tax, but extra income can make more of your Social Security taxable. The IRS uses “combined income”: your adjusted gross income, plus nontaxable interest, plus half your Social Security benefits.
- Single filers: up to 50% of benefits are taxable above $25,000 and up to 85% above $34,000.
- Married filing jointly: up to 50% above $32,000 and up to 85% above $44,000.
Those thresholds have never been adjusted for inflation, so many working retirees cross them. See whether Social Security is taxed. People 65 and older may also qualify for the new $6,000 senior tax deduction for 2025 through 2028.
How to report your earnings to SSA
- Estimate ahead. When you claim, SSA asks you to estimate your earnings for the year. If your income changes, update the estimate. You can do that by calling 1-800-772-1213 or through your my Social Security account.
- W-2 wages are reported automatically, but SSA may not process them until well into the next year. A low estimate can lead to an overpayment notice later.
- Self-employed? Your tax return reports your net earnings. You may also need to file an annual report of earnings with SSA by April 15.
If you’ve already received an overpayment notice, my guide to Social Security overpayments explains repayment plans and waivers.
Could the earnings test go away?
Bills in both chambers of Congress would repeal the earnings test. The Senior Citizens’ Freedom to Work Act of 2026 was introduced in the Senate as S. 4184 in March 2026 and in the House as H.R. 8344 in April 2026. Both were referred to committee, and neither had become law when I checked in October 2026. For now, the earnings test still applies.
Should you claim early if you’re still working?
If you expect to earn well above $24,480, claiming early usually doesn’t make sense. Much of your benefit would be withheld anyway, and you’d lock in a reduced rate for the months that are paid. Many people in that spot do better waiting until they stop working or reach FRA.
Claiming early while working can make sense if your earnings are close to the limit, you need the income now, or health concerns make an earlier claim worthwhile. Run the numbers with SSA’s calculators before you file.
FAQ
How much can I earn on Social Security in 2026?
If you’re under full retirement age all year, $24,480. In the year you reach full retirement age, $65,160 (counting only months before you reach it). After that, there’s no limit.
Do withheld benefits get paid back?
Yes, gradually. At full retirement age, SSA permanently raises your monthly benefit to credit the months it withheld.
Does pension or 401(k) income count toward the earnings limit?
No. Only wages and net self-employment earnings count.
Is there an earnings limit after age 67?
No. Once you reach full retirement age, you can earn any amount without benefits being withheld.
Does the earnings test apply to SSI or disability benefits?
No. SSI and SSDI have different work rules. SSDI uses “substantial gainful activity” limits, and SSI counts most income.
Related guides
The $90 Medicare Part B Rebate: Who Gets It, When It Arrives, and What to Watch For
my Social Security Account in 2026: How to Sign In With Login.gov or ID.me, Fix Common Problems and Stay Safe
Living on Social Security Alone in 2026 and 2027: The Real Numbers and 7 Programs That Can Close the Gap