Medicare Savings Programs 2026: QMB, SLMB, QI and QDWI Limits, What They Pay and How to Apply

Medicare Savings Programs (MSPs) are four state-run programs that pay some or all of your Medicare costs if your income and savings are limited. The most generous one, QMB, covers your Part B premium, your deductibles and your 20% coinsurance. The other three cover a premium only. In 2026 the Part B premium alone is $202.90 a month, so even the smallest program is worth about $2,435 a year.
Every program also comes with something many people miss. Qualifying for any MSP automatically qualifies you for Extra Help with Part D drug costs.
I’m a researcher who reads Medicare’s rules closely. I’m not a licensed agent or a benefits counselor. The limits and rules below come from Medicare.gov and CMS, and I link to them. For free one-on-one help with an application, contact your State Health Insurance Assistance Program (SHIP).
If you also get Extra Help, learn what the tan, blue and orange Medicare letters say and what to do.
The 4 programs at a glance (2026 limits)
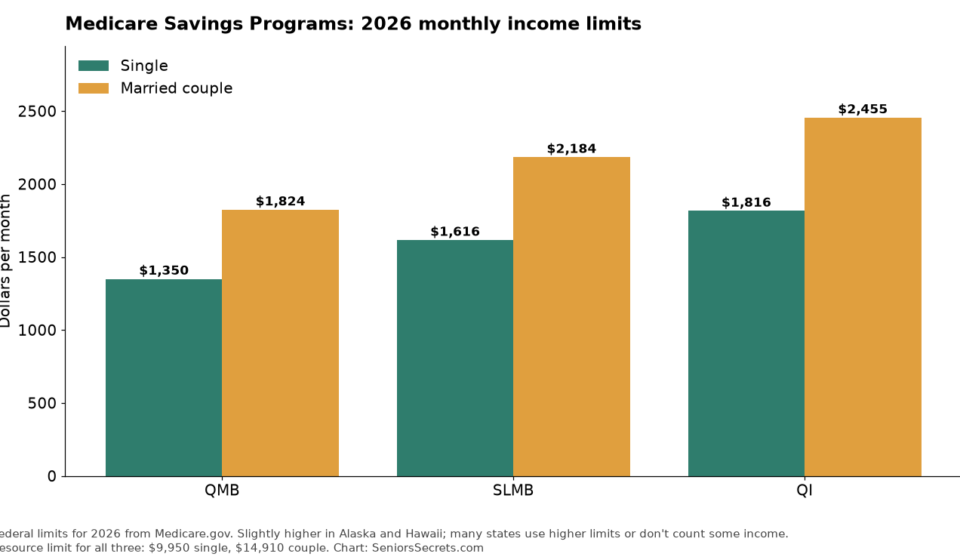
These are the federal limits Medicare.gov publishes for 2026. Income limits are monthly and slightly higher in Alaska and Hawaii.
| Program | What it pays | Monthly income limit (single / couple) | Resource limit (single / couple) |
|---|---|---|---|
| QMB (Qualified Medicare Beneficiary) | Part A premium if you owe one, Part B premium, deductibles, coinsurance and copays | $1,350 / $1,824 | $9,950 / $14,910 |
| SLMB (Specified Low-Income Medicare Beneficiary) | Part B premium | $1,616 / $2,184 | $9,950 / $14,910 |
| QI (Qualifying Individual) | Part B premium | $1,816 / $2,455 | $9,950 / $14,910 |
| QDWI (Qualified Disabled and Working Individual) | Part A premium only | $5,405 / $7,299 | $4,000 / $6,000 |
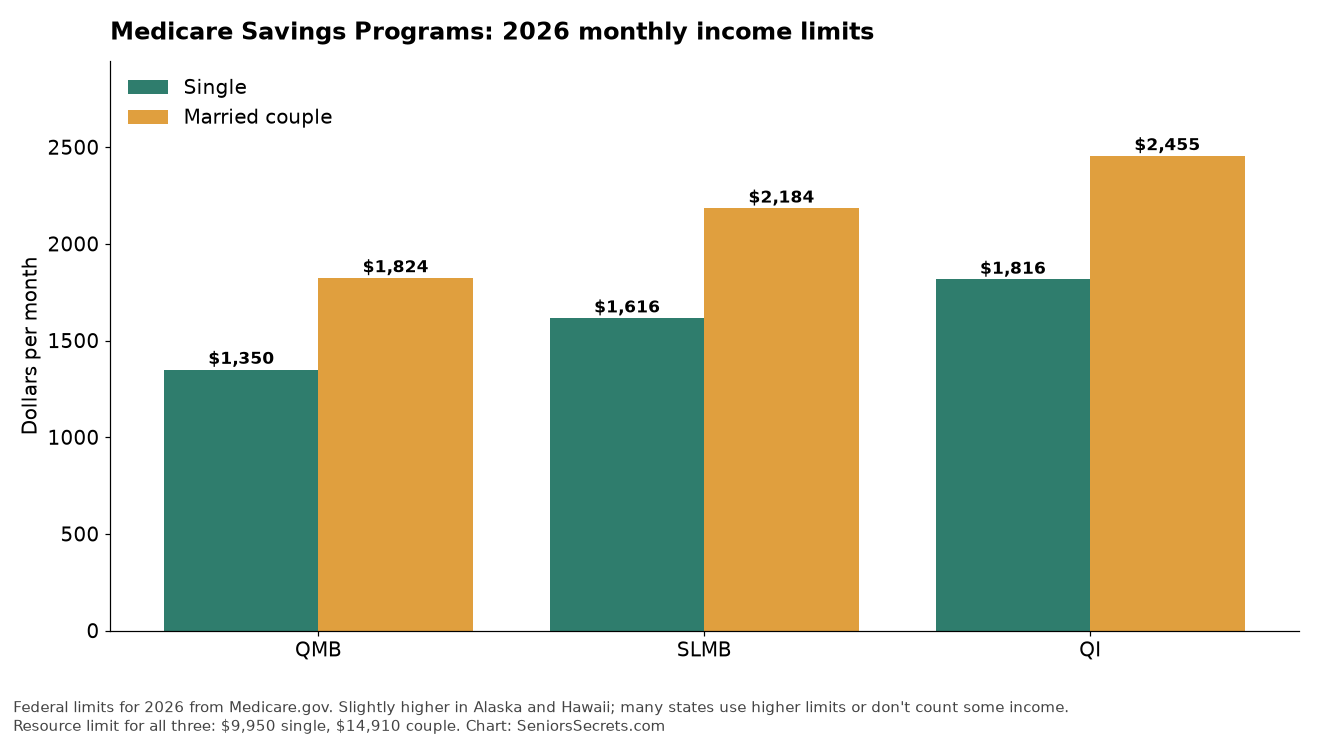
Two things about this table trip people up.
Your state may be more generous. Medicare.gov says plainly that you may qualify even if your income or resources are above these figures, because some states don’t count certain income or resources at all. The federal numbers are a floor, not a ceiling. That’s why Medicare’s own advice is to apply even if you don’t think you qualify.
Not everything counts as a resource. Resources are things like checking and savings accounts, stocks, bonds, mutual funds and IRAs. Your home, one car, a burial plot, up to $1,500 set aside for burial expenses, and your furniture and household items don’t count.
What each program is worth in dollars
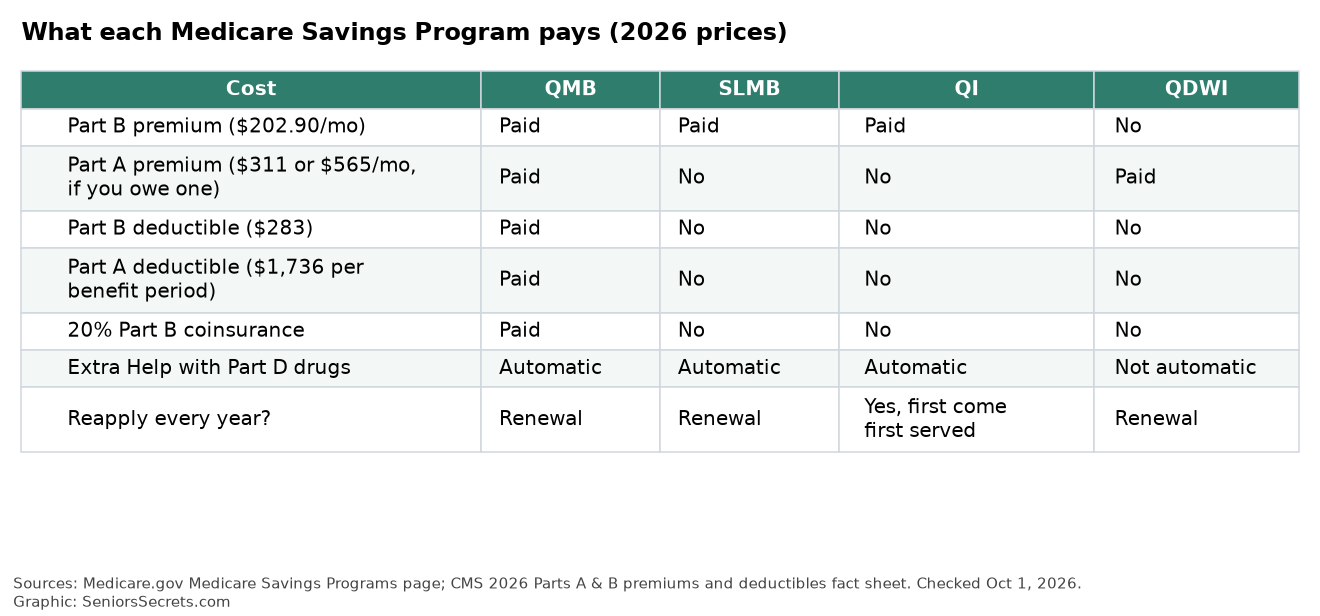
Here’s what the programs pay at 2026 prices, using the CMS 2026 premium and deductible figures.
QMB: the full package
QMB pays:
- The Part B premium: $202.90 a month, or $2,434.80 a year.
- The Part B deductible: $283.
- Your 20% Part B coinsurance on doctor visits, outpatient care, tests and equipment.
- The Part A hospital deductible: $1,736 per benefit period, plus the daily hospital and skilled nursing copays if you have a long stay.
- The Part A premium, if you don’t get Part A free. That premium is $311 or $565 a month in 2026, depending on your work history.
The protection that matters most day to day is billing. If you’re in QMB, Medicare providers aren’t allowed to bill you for Medicare-covered services and items, including deductibles, coinsurance and copays. You may still owe a small Medicaid copay where one applies. Show your Medicare card and your Medicaid or QMB card every time you get care.
If a provider bills you anyway, don’t just pay it. Tell them you’re in QMB, show the card, and call 1-800-MEDICARE if the bill doesn’t go away.
SLMB and QI: the Part B premium
SLMB and QI both pay the Part B premium, which is worth $2,434.80 a year in 2026. You still pay your own deductibles and coinsurance. The difference between them is the income band and how secure the money is:
- SLMB works like an entitlement. If you qualify, you get it.
- QI is funded with a fixed amount each year. States approve applications first come, first served, give priority to people who had QI the year before, and require you to reapply every year. QI is only for people who don’t qualify for any other Medicaid coverage.
QDWI: Part A for people with disabilities who work
QDWI is narrow. It’s for people under 65 who lost premium-free Part A because they went back to work after a disability. It pays the Part A premium only, which can be up to $565 a month in 2026.
The automatic bonus: Extra Help with drug costs
If you qualify for QMB, SLMB or QI, you automatically get Extra Help paying for Part D drugs. You don’t file a second application.
In 2026, Medicare.gov says people in these programs pay no more than $12.65 for each covered drug. In 2027, Extra Help copays are no more than $5.80 for a generic and $14.40 for a brand-name drug, according to Medicare.gov’s Extra Help page. People who have full Medicaid and are in QMB pay no more than $4.90.
For anyone on several brand-name drugs, this can be worth more than the premium help itself. A standard Part D plan can charge a deductible of up to $700 in 2027 plus 25% coinsurance, up to the new $2,400 yearly cap. I cover those changes in my Part D 2027 guide.
Two more benefits people overlook
No more Part B late enrollment penalty. If you’ve been paying a Part B penalty for signing up late, enrolling in a Medicare Savings Program generally ends it. Medicare.gov’s penalty page says you generally won’t pay a Part B penalty if you enroll in an MSP. Penalties are 10% of the premium for each full year you went without Part B, for life, so this can be a meaningful extra saving. My guide to the General Enrollment Period and late penalties explains how the penalty is calculated.
Your Social Security check goes up. Most people have the Part B premium taken out of their Social Security payment. Once the state starts paying it, that deduction stops, and your monthly deposit rises by the premium amount. The switch can take a few months to show up.
A worked example
Take a single woman, 72, whose only income is a $1,300 Social Security payment and who has $6,000 in savings. She’s under both QMB limits in 2026 ($1,350 income, $9,950 resources).
If her state approves her for QMB:
- Her Social Security deposit rises by $202.90 a month because she no longer pays the Part B premium.
- She owes nothing toward the $283 Part B deductible or her 20% coinsurance at Medicare providers.
- If she’s hospitalized, she doesn’t pay the $1,736 Part A deductible.
- Her drug copays drop to Extra Help levels, no more than $12.65 per drug in 2026.
Now change one number. Say her Social Security is $1,500 instead. She’s over the QMB limit but under SLMB’s $1,616. She’d get her Part B premium paid and Extra Help, but she’d still owe her own deductibles and coinsurance. That’s still about $2,435 a year in premiums alone, before any drug savings.
How to apply
Medicare Savings Programs are run by your state, usually through the state Medicaid office. You apply with the state, not with Medicare or Social Security. Your state decides which program you qualify for.
- Find your state’s office. Medicare.gov links to every state’s Medicaid agency, and your SHIP counselor can tell you exactly where to send the form.
- Gather your documents. Have your Medicare card, Social Security award letter, any pension statements, recent bank statements, and proof of where you live.
- Apply even if you’re slightly over. States may disregard some income, and some don’t count certain assets at all.
- Watch the start date. QMB begins the month after the state approves you, and it doesn’t pay for earlier months. SLMB and QI can start in the month you apply and can be backdated up to three months if you qualified then. That’s one reason to apply as soon as you think you might qualify.
- Mark your calendar if you get QI. You must reapply every year, and early applications get priority.
Can I keep my Medicare Advantage plan?
Yes. You can be in an MSP and a Medicare Advantage plan at the same time. The state pays your Part B premium either way, and QMB billing protections apply to in-network Medicare Advantage providers too. Some people who get QMB also qualify for a Dual Eligible Special Needs Plan. My D-SNP enrollment guide explains how those plans work.
If your income is too high for any MSP but you need long-term care, look at Medicaid spend-down rules, which work differently.
What changes for 2027
The 2027 MSP limits won’t be known until the federal poverty guidelines update in early 2027. The limits are tied to those guidelines, which usually rise each year. The Part B premium for 2027 also hadn’t been announced when I checked on October 1, 2026. I’ll update this post when both are out.
What’s already set for 2027 makes these programs worth more. The Extra Help copays you get with any MSP drop to $5.80 and $14.40, and the Part D cap rises to $2,400. For the full list, see my guide to Medicare changes for 2027.
FAQ
What is the income limit for QMB in 2026?
$1,350 a month for an individual and $1,824 for a married couple, with resource limits of $9,950 and $14,910. Many states use higher limits or don’t count some income or assets.
Does a Medicare Savings Program reduce my Social Security?
No. It usually increases your deposit, because Social Security stops taking the Part B premium out once the state pays it.
Will my state take my house after I die?
Not for Medicare Savings Program benefits. Federal law has exempted MSP cost-sharing from Medicaid estate recovery since 2010. Full Medicaid long-term care benefits follow different rules, so check with your state if you also get those.
Do I have to reapply every year?
For QI, yes. For QMB and SLMB, states renew eligibility periodically, usually once a year. Return any renewal form your state sends so your coverage doesn’t lapse.
Is QMB the same as Medicaid?
No. QMB is a Medicare Savings Program run by your state Medicaid agency. Some people have QMB only, and others have QMB plus full Medicaid. Both groups get the billing protections and Extra Help.