
There’s no single “best” Medicare plan. There’s the plan that costs you the least over a year for the drugs you take, the doctors you see and the pharmacy you use, in your ZIP code. Finding it takes about an hour with Medicare’s free Plan Finder, a list you can make at your kitchen table, and a few phone calls.
Open Enrollment for 2027 coverage runs October 15 to December 7, 2026, and Plan Finder already shows 2027 plans. Here’s the process I’d follow.
I’m a researcher, not a licensed insurance agent, and I don’t earn anything from any plan you choose. If you’d like a person to walk through this with you, your State Health Insurance Assistance Program (SHIP) offers free, unbiased counseling, and so does 1-800-MEDICARE.
Before you start: make your list
Plan Finder is only as good as what you tell it. Before you open it, write down:
- Every prescription, with the exact name, dose and how many you take a month. Pull out the bottles. “Metformin 500 mg, twice a day” beats “my diabetes pill.”
- Your pharmacy, plus a backup, and whether you’d use mail order.
- Your doctors and specialists, and the hospital you’d want to go to.
- Care you expect next year, like a planned surgery, physical therapy or regular specialist visits.
- What matters most to you: keeping a specific doctor, the lowest monthly premium, or protection from big bills.
Step 1: Decide which kind of coverage you’re comparing
Plan Finder compares three different things, and mixing them up causes most of the confusion:
- Medicare Advantage plans (Part C), which replace Original Medicare and usually include drug coverage. They have networks and a yearly out-of-pocket maximum.
- Stand-alone drug plans (Part D), which you add to Original Medicare.
- Medigap policies, which help pay Original Medicare’s deductibles and coinsurance. Plan Finder can show what’s sold in your area, but prices come from the insurers.
If you’re happy with Original Medicare and a Medigap policy, you’re only shopping for a Part D plan. If you’re in or considering Medicare Advantage, my Medicare Advantage 2027 guide covers how to compare those plans.
Step 2: Open Plan Finder and enter your ZIP code
Go to Medicare Plan Finder. You can log in to your Medicare.gov account, which saves your drug list and pharmacies for next time, or continue without logging in. Your Medicare.gov account now works with Login.gov, ID.me and CLEAR, according to CMS’s September announcement.
Make sure you’re looking at 2027 plans. Plan Finder shows both years during the fall, and it’s easy to compare the wrong year by mistake.
Step 3: Add your drugs and pharmacies
Enter each drug from your list, choose the right dose and quantity, then add your pharmacy or pharmacies. This is the step that makes the cost estimates meaningful. Skip it and Plan Finder will rank plans by premium, which is the least useful way to rank them.
Two 2027 numbers to keep in mind as you look at results:
- No Part D plan can charge a deductible above $700 in 2027 (up from $615).
- Your out-of-pocket drug costs are capped at $2,400 for the year (up from $2,100). After that, covered drugs cost $0.
Step 4: Sort by total cost, not premium
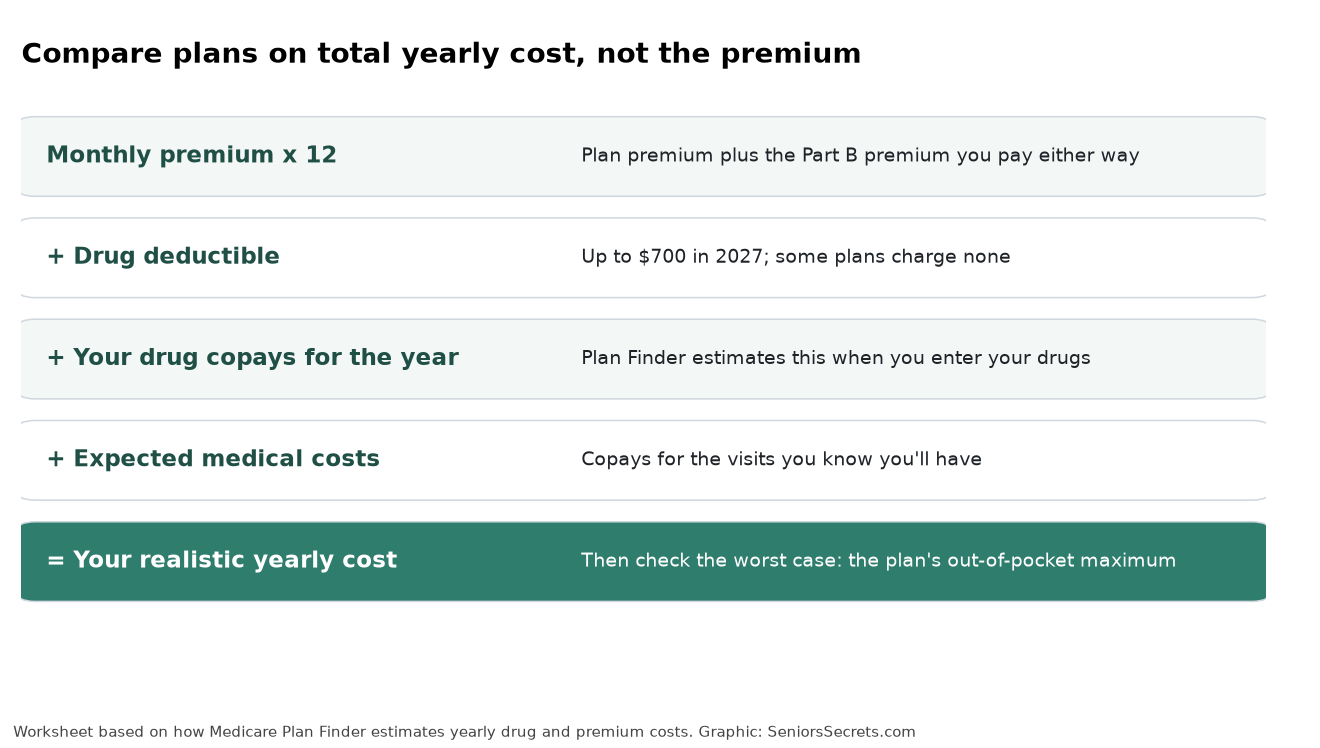
Sort the results by the lowest estimated total of drug costs plus premiums. Then, for your top three or four plans, work out a realistic yearly figure:
- Monthly plan premium times 12
- Plus the drug deductible
- Plus the estimated drug copays Plan Finder shows for your list
- Plus expected medical copays, if it’s a Medicare Advantage plan
Then look at the worst case. For Advantage plans, that’s the plan’s out-of-pocket maximum. CMS capped it at $9,850 for in-network care in 2027, though many plans set it lower. A plan with a $0 premium and an $8,000 maximum might be fine if you’re healthy and risky if you’re not.
Step 5: Check star ratings and plan details
Medicare rates plans from 1 to 5 stars on quality and customer service. Ratings aren’t everything, but a plan with consistently low ratings deserves a hard look. A plan rated 5 stars also gives you an extra option: Medicare has a Special Enrollment Period that lets you switch into a 5-star plan outside Open Enrollment.
CMS says that starting this October, Plan Finder will show more details about preventive services in health plans, link directly to plan documents like formularies and the Summary of Benefits, and flag changes affecting your current plan in 2027. Open those documents for your finalists.
Step 6: Verify the things Plan Finder can miss
Plan Finder is strong on drug costs and weaker on networks. Before you enroll:
- Call your doctors’ offices. Ask, “Will you be in network with [plan name] in 2027?” Office staff may know about network changes before online directories catch up. My guide to finding a Medicare-approved doctor has more on this.
- Call the plan. Confirm your drugs, tiers and any prior authorization or step therapy rules.
- Check your pharmacy’s status. Preferred pharmacies often have lower copays than standard in-network ones.
- If you’re leaving Medicare Advantage for Original Medicare, confirm you can get a Medigap policy first. Outside your one-time Medigap enrollment period, insurers in most cases can use medical underwriting.
Step 7: Enroll, and keep proof
You can enroll through Plan Finder, by calling 1-800-MEDICARE (1-800-633-4227, TTY 1-877-486-2048), or directly with the plan. Write down the confirmation number and the date. Your new coverage starts January 1, 2027, and the plan has to get your request by December 7.
Joining a new Medicare Advantage or Part D plan automatically ends your old one of the same kind, so you don’t need to cancel separately in most cases.
Shortcuts if your situation is simple or special
- You like your current plan: read its Annual Notice of Change, run your drugs through Plan Finder once to compare, and stay put if nothing better shows up.
- Your income is limited: check whether you qualify for Extra Help with drug costs before you compare. It changes which plans make sense.
- You’re short on time: my Open Enrollment guide has the dates and a shorter checklist.
FAQ
What’s the best Medicare plan in my area?
It depends on your drugs, doctors, pharmacy and budget. The best way to find out is to enter your drugs and pharmacy into Medicare Plan Finder for your ZIP code and compare plans by estimated total yearly cost.
Is Medicare Plan Finder free?
Yes. It’s Medicare’s official comparison tool at Medicare.gov/plan-compare, run by the federal government rather than an insurance company.
Should I use an insurance agent or broker?
That’s your choice. Agents can be helpful, but they may not represent every plan in your area. SHIP counselors give free, unbiased help and don’t sell plans.
How many plans should I compare?
Narrow to three or four using Plan Finder’s total-cost estimate, then check networks, drug rules and the out-of-pocket maximum for those finalists.
What if I pick the wrong plan?
If you’re in Medicare Advantage, you can switch once between January 1 and March 31, 2027. Some life events also give you a Special Enrollment Period.