
The 2026 Social Security cost-of-living adjustment (COLA) was 2.8%. It started with the benefit for December 2025, paid in January 2026. SSI recipients got it on December 31, 2025. SSA said the average retirement check rose by about $56 a month (SSA press release).
Medicare took a big bite. The standard Part B premium jumped $17.90, from $185.00 to $202.90 a month (CMS). Most people pay it straight out of their Social Security. So the average retiree kept about $38 of the raise.
Update, October 14, 2026: SSA has now announced the 2027 COLA. It’s 3.6%, the biggest raise since 2023. The average retired worker is expected to go from $2,094 to $2,170 a month. My full guide to the 2027 COLA and what it means for you has every new number. This page is the look back at 2026, and why the Part B premium matters so much.
For the latest on the still-pending 2027 Part B amount, see what CMS and SSA have said so far and what to do now.
The 2026 raise in numbers
The 2.8% COLA reached about 75 million people. That was nearly 71 million on Social Security and nearly 7.5 million on SSI. Some people get both (SSA).
SSA’s actuaries estimated these average amounts for the end of December 2025:
| Type of benefit | Before 2.8% COLA | After | Increase |
|---|---|---|---|
| Retired worker | $2,015 | $2,072 | $57 |
| Retired worker and aged spouse | $3,124 | $3,211 | $87 |
| Aged widow(er) living alone | $1,868 | $1,920 | $52 |
| Disabled worker | $1,585 | $1,630 | $45 |
| Widowed mother and 2 children | $3,790 | $3,896 | $106 |
Source: SSA Office of the Chief Actuary, December 2025 version of its COLA effect page (archived copy). The actuaries’ table says $57 for retired workers. The press release said “about $56.” Both are estimates, so either is fair.
How SSA got 2.8%
The COLA follows one price index, the CPI-W. It tracks what working households in cities pay for goods and services. SSA compares the average for July, August and September with the same months a year earlier.
- Third quarter 2024 average: 308.729
- Third quarter 2025 average: 317.265
- The math: (317.265 minus 308.729) divided by 308.729 = 2.8%
Source: SSA’s 2026 COLA computation (archived copy).
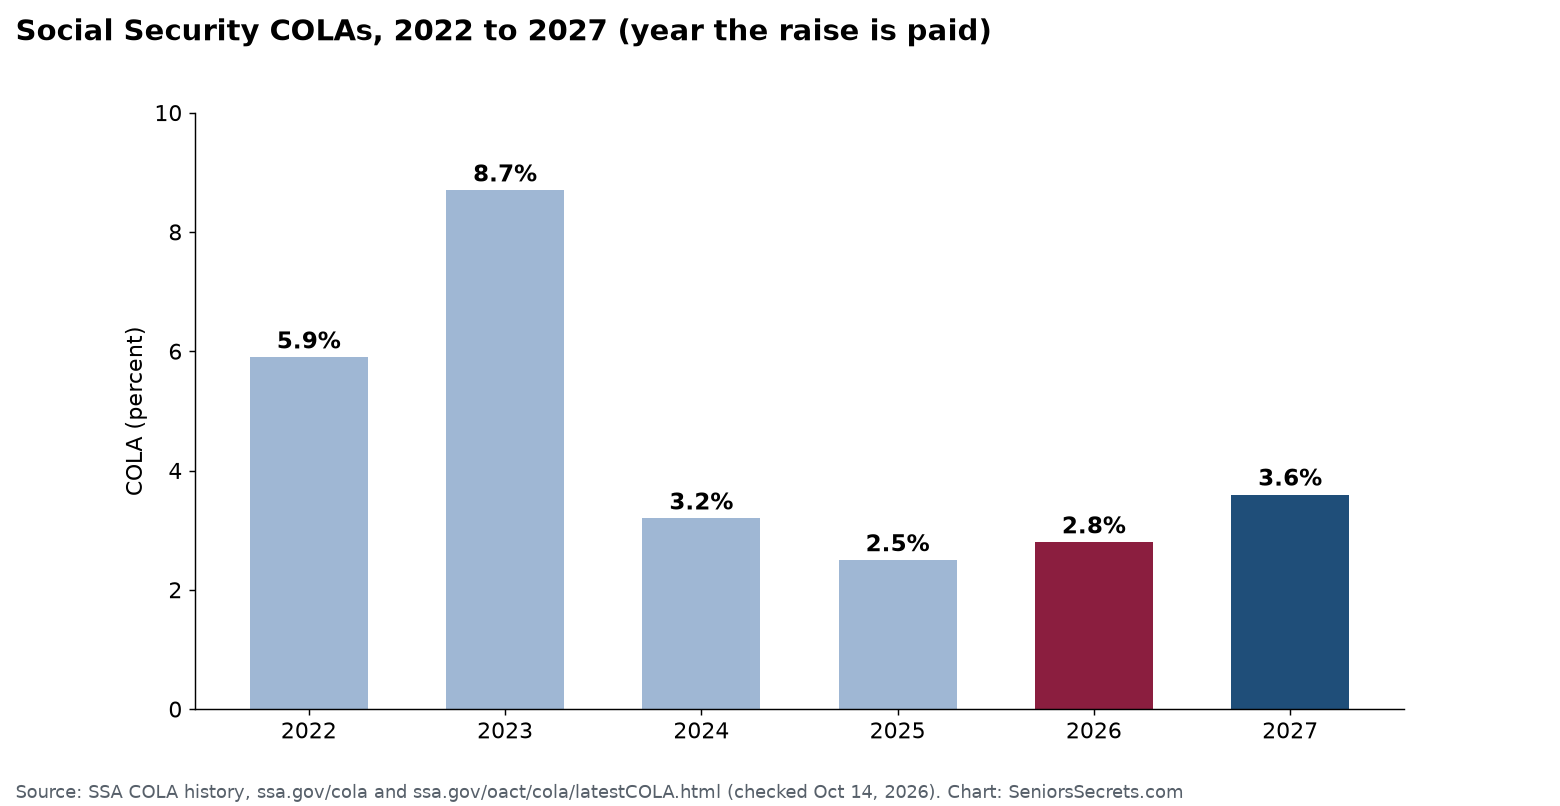
One fix to a common mix-up: the COLA paid in 2025 was 2.5%, not 3.2%. The 3.2% raise was paid in 2024 (SSA COLA history).
How much Part B took
CMS set the 2026 standard Part B premium at $202.90 a month, up $17.90 (about 9.7%). The yearly Part B deductible went from $257 to $283. CMS said the jump came mainly from expected price changes and more use of services. It also said the increase would have been about $11 a month higher without new limits on spending for skin substitutes, a type of wound care product (CMS).
The premium increase is the same dollar amount for everyone who pays the standard rate. But the raise is a percent. So the smaller your check, the more of your raise Part B took.

| Monthly benefit | 2.8% raise | Minus Part B increase | Left over |
|---|---|---|---|
| $800 | $22.40 | $17.90 | $4.50 |
| $1,200 | $33.60 | $17.90 | $15.70 |
| $2,015 (average retiree) | $56.42 | $17.90 | $38.52 |
| $3,000 | $84.00 | $17.90 | $66.10 |
This is my math. It assumes the standard premium and a full 2.8% raise. SSA rounds payments down, so real checks can be a few cents lower.
The “hold harmless” rule, and who it skipped
A rule called “hold harmless” keeps a Part B increase from making your net Social Security check smaller than the year before. If your raise in dollars is smaller than the premium increase, your premium goes up only by the amount of your raise.
In 2026, that only helped people with checks of about $639 a month or less. That’s because 2.8% of $639 is about $17.90. Someone with an $800 check was not protected. They kept just $4.50.
The rule also doesn’t cover everyone. For example, it doesn’t help people new to Medicare or people who pay the higher, income-based premium. My Part B premium guide lists who is and isn’t covered.
Higher earners paid even more. People with 2024 income above $109,000 (single) or $218,000 (joint) paid an extra charge called IRMAA. In 2026 the total Part B premium for them runs from $284.10 to $689.90 a month. CMS says about 8% of people with Part B pay it (CMS).
Why many retirees felt 2.8% wasn’t enough
The CPI-W is based on what working households buy. Retirees often spend more of their budget on health care than younger workers do. The Bureau of Labor Statistics does publish a research index for Americans 62 and older, called R-CPI-E. But BLS says it has real limits. Its sample is small, and the stores it prices may not reflect where older people shop. So no agency uses it officially (BLS). Congress would have to change the law to switch indexes, and it hasn’t.
My take: the CPI-W isn’t the main problem for most retirees. Health costs are. A raise that looks fine on paper can shrink a lot once Medicare premiums and copays come out.
What changes for 2027
- COLA: 3.6%, starting with January 2027 payments. SSI rises on December 31, 2026 (SSA).
- Average retired worker: $2,094 to $2,170, an estimated $76 more (SSA).
- 2027 Part B premium: not announced yet as of October 14, 2026. CMS posted the 2026 amounts on November 14, 2025, so a fall release is likely.
- The projection: the 2026 Medicare Trustees Report projects about $209.50 a month for 2027, or $6.60 more (AARP). That’s a projection, not the real rate.
If the real premium comes in near that projection, Part B would take a much smaller share than in 2026. The average retiree would keep about $69 of a $76 raise. Compare that with about $38 of $56 this year. I’ll update both posts once CMS posts the 2027 numbers.
How to keep more of your raise
- Medicare Savings Programs. If your income and savings are limited, your state may pay your Part B premium. At the 2026 rate that’s $2,434.80 a year. See my Medicare Savings Programs guide for the limits.
- Extra Help with drug costs. It lowers Part D premiums and copays. Here’s how to apply for Extra Help.
- Check your tax withholding. You can have 7%, 10%, 12% or 22% withheld, or none. Change it with Form W-4V or in your my Social Security account.
- Use Open Enrollment (October 15 to December 7, 2026). Compare 2027 plans. Saving on premiums and copays can be worth more than the COLA.
- Read your COLA notice. It shows your exact new benefit and what Medicare takes. If something looks wrong, call SSA at 1-800-772-1213.
Common questions
How much was the Social Security COLA for 2026?
It was 2.8%. SSA said the average retirement check rose about $56 a month starting in January 2026.
How much did the Part B premium go up in 2026?
The standard premium rose $17.90, from $185.00 to $202.90 a month. The deductible rose from $257 to $283.
What is the hold harmless rule?
It keeps a Part B premium increase from lowering your net Social Security check. In 2026 it only helped people with checks of about $639 a month or less.
What is the COLA for 2027?
SSA announced a 3.6% COLA on October 14, 2026. It starts with January 2027 payments, and SSI rises on December 31, 2026.
Will Medicare take part of the 2027 raise?
Probably, but the 2027 Part B premium isn’t announced yet. The Trustees projected about $209.50 a month. If that holds, the average retiree would keep about $69 of a $76 raise.
Written by Khasim Basha Shaik. I research Social Security and Medicare rules for readers by reading SSA and CMS sources closely. I’m not a financial advisor, tax professional or licensed insurance agent. This article summarizes official SSA, CMS, BLS and IRS materials and isn’t financial, tax or legal advice. Last reviewed October 14, 2026.