
This is the biggest Medicare decision most people make, and it is harder to undo than it looks. Original Medicare (Parts A and B) lets you see almost any doctor in the country who takes Medicare, but it has no yearly cap on what you pay. Medicare Advantage (Part C) bundles your coverage into one private plan, usually with drug coverage and extras, but it uses networks, often needs prior approval, and caps your costs at a number that can still be high.
Open Enrollment for 2027 coverage runs October 15 to December 7, 2026. Changes start January 1, 2027.
I’m a researcher who reads official Medicare pages and plan documents for readers. I am not a licensed insurance agent, and I don’t sell plans. Before you choose, compare plans in your ZIP code with Medicare’s Plan Finder at Medicare.gov, and talk to your free State Health Insurance Assistance Program (SHIP) counselor. Everything below was checked against official sources on October 5, 2026.
The short version
- Original Medicare + Medigap + Part D costs more each month, but your costs in a bad year are predictable, and you can see any provider who takes Medicare, anywhere in the U.S. No referrals, and very little prior authorization.
- Medicare Advantage often has a low or $0 premium on top of Part B, plus dental, vision and hearing extras. In exchange you accept a network, prior authorization rules, and copays that add up to a yearly limit.
- The hard part is switching back. You can usually leave Medicare Advantage for Original Medicare each year, but buying a Medigap policy later can mean answering health questions. More on that below.
Side by side for 2027
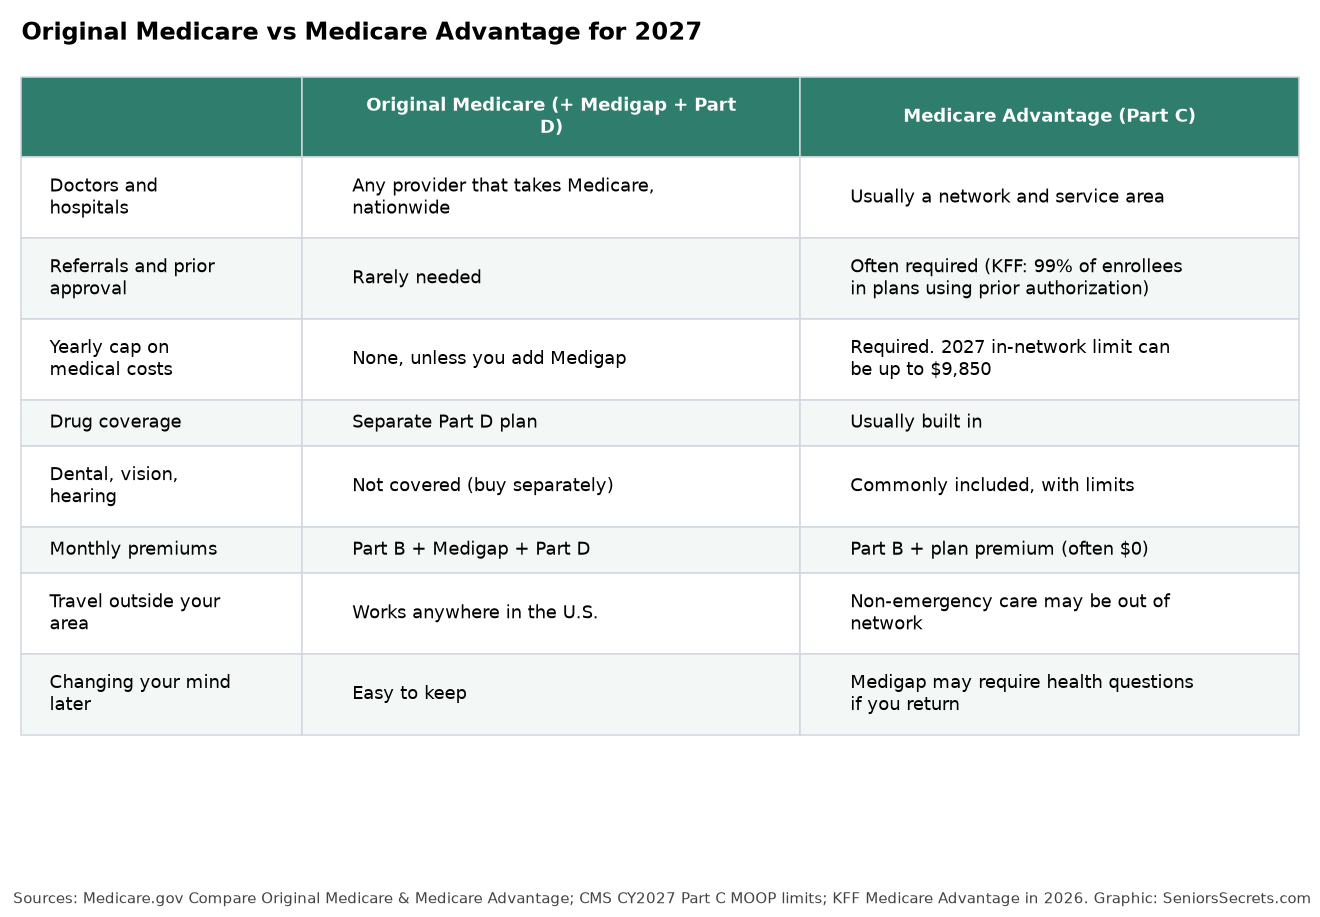
| Original Medicare (with Medigap and Part D) | Medicare Advantage (Part C) | |
|---|---|---|
| Doctors and hospitals | Any provider in the U.S. that takes Medicare | Usually a network and service area |
| Referrals and prior approval | Rarely needed | Often required |
| Yearly cap on medical costs | None, unless you buy Medigap | Required; 2027 in-network limit can be up to $9,850 |
| Drug coverage | Separate Part D plan | Usually built in |
| Dental, vision, hearing | Not covered (buy separately) | Commonly included, with limits |
| Monthly premiums | Part B + Medigap + Part D | Part B + plan premium (often $0) |
| Travel outside your area | Works anywhere in the U.S. | Non-emergency care may be out of network |
These rules come from Medicare’s own comparison of Original Medicare and Medicare Advantage. Both options must cover the same Part A and Part B services. The difference is how you get care and how you pay.
What the money looks like
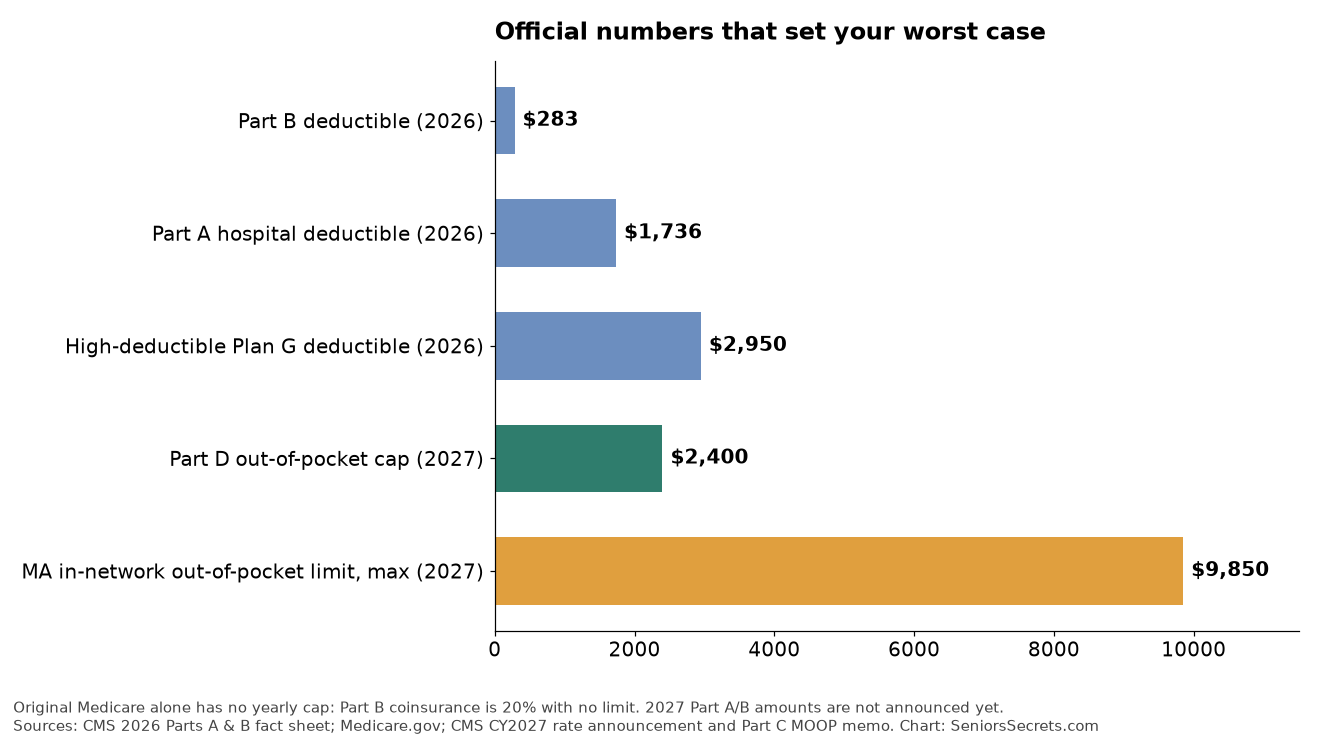
Everyone pays the Part B premium. In 2026 that is $202.90 a month, with a $283 yearly Part B deductible. CMS hasn’t announced the 2027 Part B or Part A amounts yet; they usually come out in the fall. I’ll update this page when they do.
On Original Medicare alone, you pay 20% of most Part B costs with no limit, plus a Part A hospital deductible of $1,736 per benefit period in 2026. That’s why most people on Original Medicare add a Medigap policy. Medigap Plan G, for example, covers almost everything except the Part B deductible. Our Plan G vs Plan N comparison walks through the two most popular options.
On Medicare Advantage, you pay copays and coinsurance until you hit the plan’s out-of-pocket limit. CMS set the 2027 maximum at $9,850 for in-network care and $14,800 for in- and out-of-network care combined (up from $9,250 and $13,900 in 2026), according to its final 2027 Part C bid memo. Many plans set a lower limit. KFF found the average in-network limit in 2026 was $5,421.
Drug costs are capped either way. In 2027 the Part D out-of-pocket cap is $2,400, whether your drug coverage comes from a standalone Part D plan or a Medicare Advantage plan. See our 2027 Part D guide for details.
My honest take: Medicare Advantage tends to look cheaper for healthy people in a quiet year. Original Medicare with a good Medigap plan tends to look cheaper in a year with a cancer diagnosis, a hip replacement or a long hospital stay. You’re really choosing which kind of year you want to be protected against.
What the national numbers say
KFF’s look at Medicare Advantage in 2026 is the best public snapshot I know of:
- About 35.2 million people, or 55% of eligible beneficiaries, are in Medicare Advantage.
- 75% of people in Medicare Advantage plans with drug coverage pay no premium beyond Part B.
- 99% of enrollees are in plans that require prior authorization for some services.
- Nearly all enrollees are in plans offering vision, dental and hearing extras, but over-the-counter benefits dropped from 79% to 68% of enrollees between 2025 and 2026.
That prior authorization number is the one I’d think about hardest. It means a plan can require approval before covering many tests, procedures or stays. Plans are also starting to use automated tools in those reviews; our prior authorization guide explains what changed and how to appeal.
The Medigap catch most people miss
You can’t use a Medigap policy with Medicare Advantage. That sounds like a footnote, but it’s the main reason this decision is hard to reverse.
Your best chance to buy Medigap is your 6-month Medigap Open Enrollment Period, which starts when you’re 65 or older and enrolled in Part B. During that window, insurers can’t turn you down or charge more because of your health. After it ends, in most situations an insurer can ask health questions and decline you or charge more.
There are some protections. Medicare’s page on when you can buy Medigap lists situations with guaranteed rights, including a “trial right” if you joined Medicare Advantage when first eligible at 65 and leave within the first year. You generally need to apply within 63 days after your Medicare Advantage coverage ends. A few states have broader rules, so ask your SHIP counselor.
If you’re already thinking about leaving a plan, our guide to switching from Medicare Advantage to Original Medicare covers the timing step by step.
Who tends to do better with each
Original Medicare plus Medigap often fits if you:
- Have a chronic condition or see several specialists
- Want to keep a specific doctor or hospital system, or use a major cancer center
- Split the year between two states
- Can afford a Medigap premium now, especially during your Medigap Open Enrollment window
Medicare Advantage often fits if you:
- Are in good health and want a low monthly premium
- Are happy with the doctors and hospitals in a local network
- Value dental, vision or hearing extras (check the dollar limits)
- Like having medical and drug coverage in one plan with one card
Neither list is a rule. Some people with health conditions do well in a strong local plan with their doctors in network. Some healthy people choose Original Medicare simply because they never want to deal with prior authorization.
A five-step way to decide this fall
- List your doctors, hospitals and prescriptions. Check each one in Plan Finder. A plan that doesn’t include your cardiologist isn’t cheap.
- Price a bad year, not just a good one. For each Medicare Advantage plan, look at its out-of-pocket limit. For Original Medicare, add up Part B, Medigap and Part D premiums for 12 months.
- Check prior authorization and referral rules in the plan’s Evidence of Coverage.
- Find out whether you can still buy Medigap without health questions, before you leave or skip it.
- Get a free second opinion from your SHIP counselor before December 7.
Our 2027 Open Enrollment guide has dates, plan-change rules and a checklist.
Already in Medicare Advantage and want to switch back?
You have two regular chances each year, plus a few special ones. Per Medicare.gov’s enrollment periods page:
| When | What you can do | Coverage starts |
|---|---|---|
| Open Enrollment, Oct 15–Dec 7 | Drop your Medicare Advantage plan and return to Original Medicare, and pick a stand-alone Part D plan | January 1 |
| Medicare Advantage Open Enrollment, Jan 1–Mar 31 | Make one switch: back to Original Medicare (and join a drug plan) or to another Advantage plan | First of the month after the request |
| Special situations | Your plan leaves Medicare or your area, you move, or the plan didn’t follow the rules | Depends on the situation |
Line up Medigap before you leave, not after. Outside your one-time Medigap Open Enrollment Period, there’s usually no federal guarantee an insurer will sell you a policy, and it may cost more because of your health history. You do have a guaranteed right to buy one in a few cases listed on Medicare.gov’s Medigap timing page: if you joined an Advantage plan when you first got Medicare and leave within the first 12 months, if you dropped a Medigap policy to try Advantage for the first time and switch back within 12 months, or if your plan is leaving Medicare or your area. In those cases you can apply up to 60 days before your Advantage coverage ends and no more than 63 days after.
The order I’d follow: apply for the Medigap policy and get accepted, then enroll in a stand-alone Part D plan for the same start date. Joining a Part D plan generally moves you out of the Advantage plan automatically, but call 1-800-MEDICARE to confirm the switch went through, and keep every letter in case you need to prove when your coverage ended.
FAQ
Is Medicare Advantage cheaper than Original Medicare?
Often in monthly premiums, yes. 75% of people in Medicare Advantage plans with drug coverage pay nothing beyond Part B, according to KFF. But your costs when you’re sick can be higher, up to the plan’s out-of-pocket limit (as high as $9,850 in-network for 2027).
Can I switch from Medicare Advantage back to Original Medicare?
Yes, during Open Enrollment (October 15 to December 7) or the Medicare Advantage Open Enrollment Period (January 1 to March 31). The catch is Medigap: outside your guaranteed rights, an insurer may use health questions.
Does Original Medicare have an out-of-pocket maximum?
No. Original Medicare alone has no yearly limit on what you pay. Medigap Plans K and L have their own limits, and most other Medigap plans cover most of the gaps.
Do I still pay the Part B premium with Medicare Advantage?
Yes. You keep paying the Part B premium ($202.90 a month in 2026), plus any plan premium. Some plans reduce your Part B premium, but often by a small amount.
Which is better if I travel?
Original Medicare works with any provider that takes Medicare across the U.S. Medicare Advantage plans usually cover emergencies anywhere, but routine care outside the plan’s area may not be covered. Neither generally covers care outside the U.S., though several Medigap plans include foreign travel emergency coverage.
Facts checked against Medicare.gov, CMS and KFF on October 5, 2026. 2027 Part A and Part B amounts haven’t been announced yet; this page will be updated when CMS publishes them. This article is for education, not personal insurance advice.