
If you are on Original Medicare and shopping for a Medigap (Medicare Supplement) policy, the shortlist usually collapses to Plan G and Plan N. Both close the scary 20% Part B coinsurance gap. Both are standardized by federal rules, so a Plan G from Company A covers the same medical benefits as a Plan G from Company B in your state. The premiums are what change.
This is a side-by-side of those standardized benefits, using Medicare.gov’s Compare Medigap Plan Benefits chart, plus a simple way to think about premium versus copays. It is meant for Open Enrollment season planning, even though Medigap itself does not use the October 15–December 7 window the way Advantage and Part D do.
I’m a researcher, not a licensed insurance agent. I can’t quote your premium or underwrite you. For personal help, use your SHIP counselor or your state insurance department.
What both plans cover the same way
According to Medicare.gov, both Plan G and Plan N cover:
- Part A coinsurance and hospital costs up to an additional 365 days after Medicare benefits are used
- Part A deductible
- Part A hospice coinsurance or copayment
- Skilled nursing facility care coinsurance
- First three pints of blood
- Part B coinsurance or copayment (with the Plan N exceptions below)
- Foreign travel emergency coverage at 80%, up to plan limits (after the plan’s foreign-travel deductible)
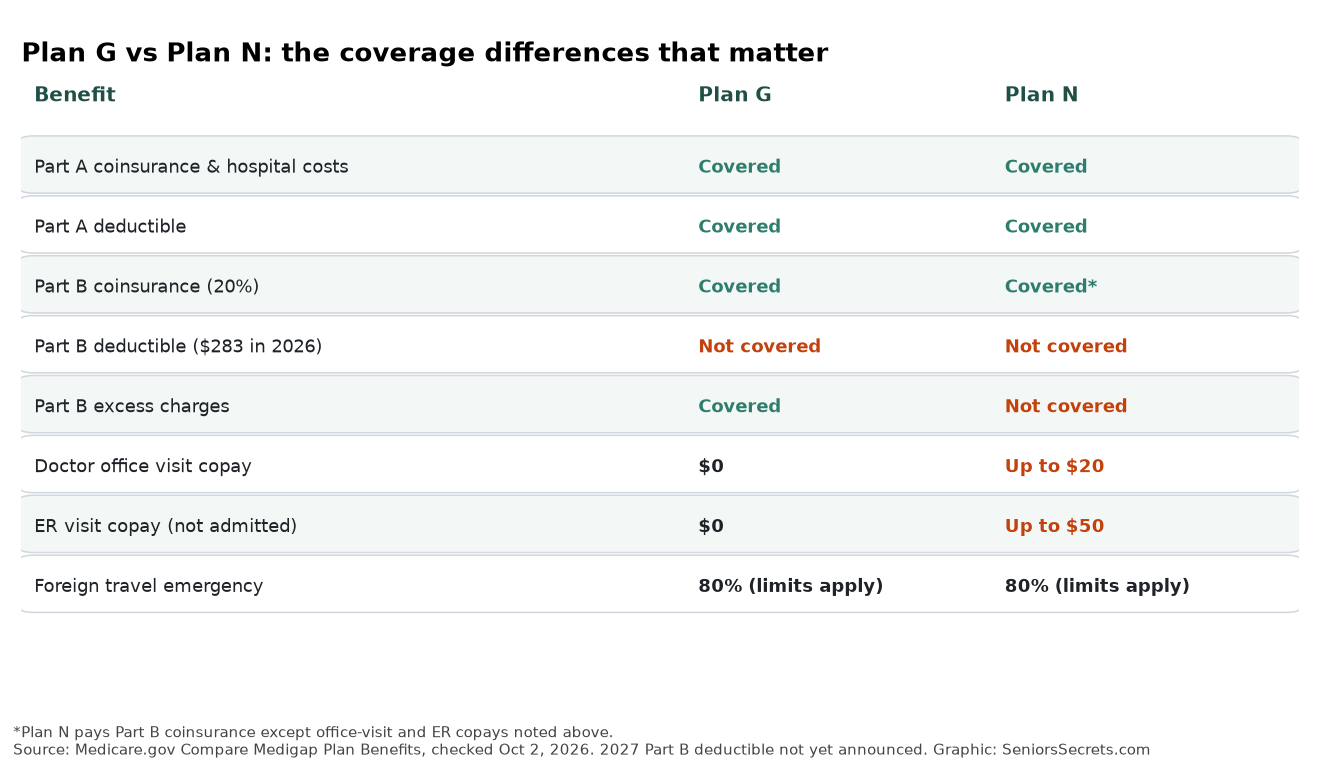
Neither Plan G nor Plan N covers the Part B deductible. For 2026 that deductible is $283. As of October 2, 2026, CMS has not announced the 2027 Part B deductible or premium. When those figures post, your out-of-pocket for the year shifts by that amount under either letter plan.
Where Plan G and Plan N actually differ
| Item | Plan G | Plan N |
|---|---|---|
| Part B deductible | Not covered (you pay it) | Not covered (you pay it) |
| Part B excess charges | Covered | Not covered |
| Some doctor office visits | $0 after Part B deductible | Copay up to $20 |
| ER visit if not admitted | $0 | Copay up to $50 (waived if you are admitted as an inpatient) |
| High-deductible option | Available in some states ($2,950 deductible in 2026 before the policy pays) | Not the high-deductible G product |
Medicare.gov’s footnote on Plan N is specific: Plan N pays 100% of Part B coinsurance except those office-visit and ER copays.
Part B excess charges, in plain English
Most doctors who take Medicare accept assignment: they agree to Medicare’s approved amount. A smaller group of non-participating providers can charge up to 15% above that amount. Those extras are Part B excess charges. Plan G covers them. Plan N does not.
Before you pick Plan N to save on premium, check whether your doctors accept assignment (Medicare Care Compare and your clinic billing office are the usual places to ask). If you mostly see assignment-accepting providers, excess charges may never show up. If you don’t, Plan N can get expensive fast.
Premiums: shop the company, not the letter
I am not going to invent a national “average” Plan G or Plan N premium. Medigap rates vary by insurer, age, ZIP code, tobacco use, household discounts, and whether your state uses attained-age, issue-age, or community rating. Coverage is standardized. Price is not.
Practical shopping rules:
- Get quotes for the same letter plan from several companies in your state.
- Compare the rate for your age today and ask how the company raises rates as you age.
- Confirm whether the quote is for Plan G, high-deductible Plan G, or Plan N.
- Use Medicare’s tools and your state department of insurance. Start at Medicare.gov Medigap.
For Plan G alone (rates, states, and what “best” actually means), see Medicare Plan G 2027 complete guide and Plan G 2027 rates guide. Those posts go deeper on Plan G; this one stays on the G-versus-N decision.
A simple break-even check (not a quote)
Suppose Plan G costs $40 a month more than Plan N from the same company in your ZIP. That is $480 a year. At Plan N’s maximum $20 office copay, it takes about 24 copay-eligible visits in a year for those copays alone to match the extra Plan G premium. ER copays of up to $50 shrink that gap faster.
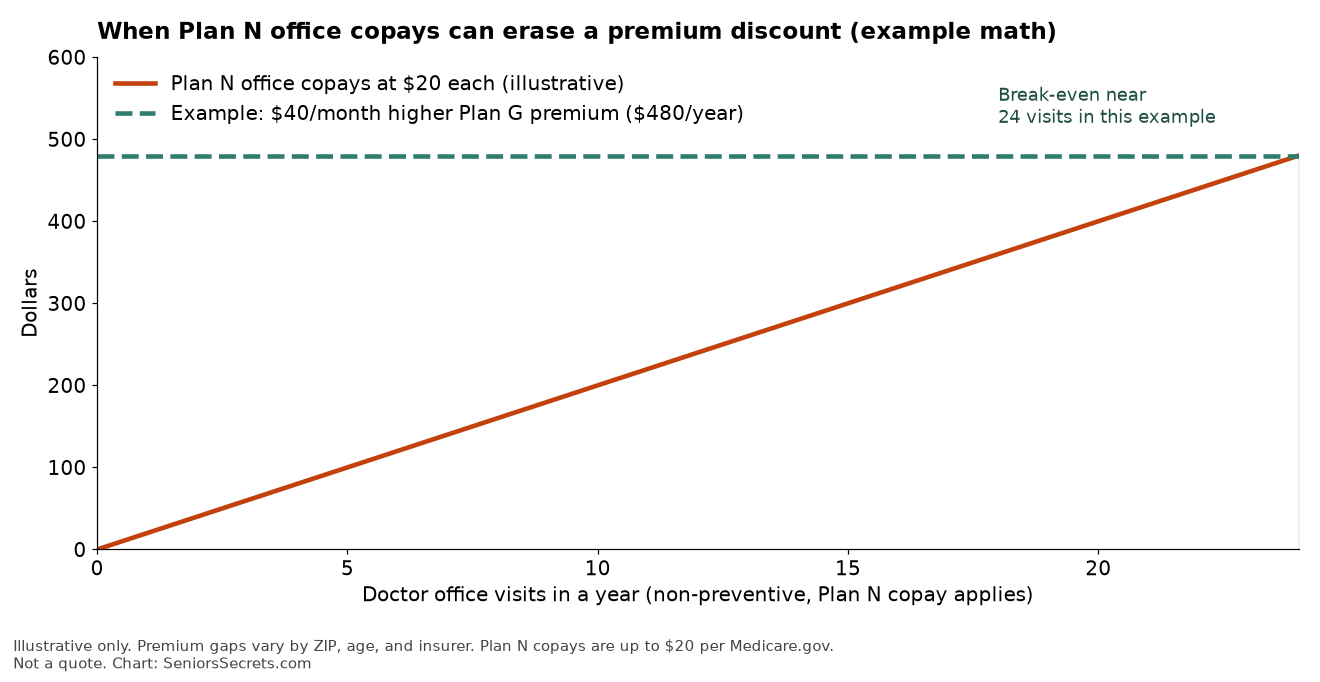
This is illustrative. Your premium gap might be $15 a month or $70. Preventive services that Medicare covers at $0 usually do not trigger the Plan N office copay the same way a problem-oriented visit does, but billing details vary—ask the plan how it applies the copay.
Plan G tends to fit better if you expect frequent specialist visits, want predictable bills after the Part B deductible, or see providers who might bill excess charges.
Plan N tends to fit better if you are generally healthy, your doctors accept assignment, and you would rather keep the monthly premium lower and pay small copays when you go.
Timing matters more than the letter
Federal Medigap Open Enrollment lasts six months, starting the first month you are 65 or older and enrolled in Part B. During that window, you generally have guaranteed issue rights for Medigap. Outside it, insurers in most states can use medical underwriting unless you have a separate guaranteed-issue right (for example, certain loss-of-coverage situations).
That is why the Advantage-to-Original-Medicare switch deserves a pause. Medicare Open Enrollment lets you move to Original Medicare between October 15 and December 7, but buying Plan G or N afterward may require underwriting. If premiums are the blocker, check Medicare Savings Programs for Part B premium help, and read switching from Medicare Advantage to Original Medicare before you drop Advantage.
In many states it is easier to start with Plan G and later ask about moving to Plan N than to start with N and try to upgrade after a new diagnosis. Rules vary—confirm with your SHIP counselor.
FAQ
Is Plan G or Plan N better for 2027?
Neither letter is universally better. Plan G removes more variable bills (no office/ER copays, covers excess charges). Plan N usually has a lower premium in return for those copays and no excess-charge coverage. The better plan is the one whose total cost matches how you use care.
Do Plan G and Plan N cover prescriptions?
No. Medigap does not include Part D. If you have Original Medicare plus Medigap, you generally still want a separate Part D plan. For 2027 Part D numbers, see Medicare Part D 2027.
Can I switch from Plan N to Plan G during Medicare Open Enrollment?
Medicare’s October 15–December 7 Open Enrollment is for Advantage and Part D, not a federal Medigap open season. Switching Medigap letter plans later often means a new application and possible underwriting, unless you have a guaranteed-issue right or your state adds protections.
What about high-deductible Plan G?
In some states, insurers sell a high-deductible Plan G. Medicare.gov says you pay Medicare-covered costs up to $2,950 in 2026 before that policy pays. It is a different product from standard Plan G. Compare it only if you can handle that deductible.
Bottom line
Plan G and Plan N are close cousins. Read the excess-charge and copay rows first, get real quotes in your ZIP, and confirm your doctors accept assignment before you trade coverage for a lower premium. Then decide with numbers, not with a national average that does not exist.