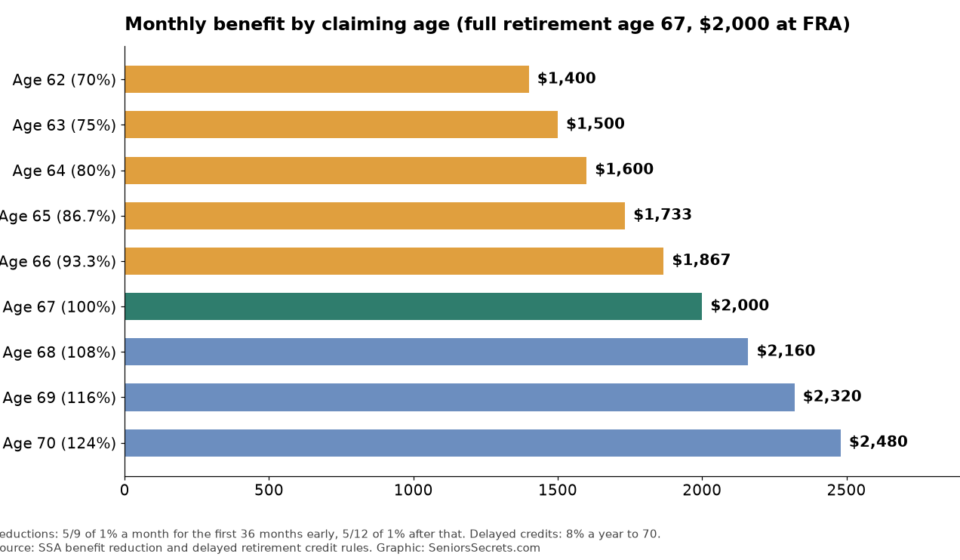
Full Retirement Age Is 67: How Claiming at 62, 67 or 70 Changes Your Social Security Check (2026 Guide)

For anyone born in 1960 or later, full retirement age (FRA) for Social Security is 67. That’s the age when you get 100% of the benefit you’ve earned. You can claim as early as 62 for a permanently smaller check, or wait until 70 for a permanently larger one. If your full benefit is $2,000, that’s the difference between about $1,400 a month at 62 and $2,480 at 70.
People born in 1960 turn 66 in 2026, so they’re the first group to face the full age-67 rule as they plan their claims. Below are the exact reductions and credits, break-even ages worked out step by step, the 2026 maximums, and the factors that should drive your decision more than any break-even chart.
I’m a researcher, not a financial planner. The rules and figures come from the Social Security Administration, mainly its pages on retirement age by birth year and delayed retirement credits. Confirm your own estimate with SSA before you file.
Full retirement age by birth year
Congress raised the full retirement age in 1983, phasing it in two months at a time. The phase-in is now complete.
| Year of birth | Full retirement age |
|---|---|
| 1943–1954 | 66 |
| 1955 | 66 and 2 months |
| 1956 | 66 and 4 months |
| 1957 | 66 and 6 months |
| 1958 | 66 and 8 months |
| 1959 | 66 and 10 months |
| 1960 and later | 67 |
Born on January 1? Social Security treats you as born in the previous year, so use that year’s row. Someone born January 1, 1960, has an FRA of 66 and 10 months.
Full retirement age has nothing to do with Medicare. Medicare eligibility still starts at 65, even if you delay Social Security. If you’re not collecting benefits, you have to sign up for Medicare yourself, or you risk lifelong penalties. My guide to Medicare late enrollment penalties explains how to avoid them.
How much you lose by claiming early, and gain by waiting
Your benefit at full retirement age is called your primary insurance amount (PIA). Claiming at any other age changes it permanently.
Claiming early. Your benefit drops by 5/9 of 1% for each of the first 36 months before FRA, and by 5/12 of 1% for each month beyond that. With an FRA of 67, claiming at 62 is 60 months early:
- First 36 months: 36 × 5/9% = 20%
- Next 24 months: 24 × 5/12% = 10%
- Total reduction: 30%, so you get 70% of your PIA
Waiting past FRA. You earn delayed retirement credits of 2/3 of 1% a month, or 8% a year, until 70. Waiting from 67 to 70 adds 24%, so you get 124% of your PIA. Credits stop at 70, so there’s no reason to wait longer.

Cost-of-living adjustments apply to whatever benefit you lock in. A larger base means larger COLA raises in dollar terms for life.
The 2026 maximum benefits
The largest possible benefits go to people who earned at or above the taxable maximum ($184,500 in 2026) for 35 years. According to SSA’s 2026 figures, someone with that history who starts benefits in 2026 would get:
| Starting age in 2026 | Maximum monthly benefit |
|---|---|
| 62 | $2,969 |
| Full retirement age | $4,152 |
| 70 | $5,181 |
Most people get far less. The average retired-worker benefit in January 2026 was $2,071 a month after the 2.8% COLA.
Break-even math: when does waiting pay off?
The break-even age is the point when the bigger, later checks catch up with the smaller checks you would have collected by claiming early. Here’s the math for someone with a $2,000 PIA and an FRA of 67:
62 vs. 67. Claiming at 62 pays $1,400 a month, so by 67 you’ve collected $84,000. Waiting pays $600 more a month from 67 on. $84,000 ÷ $600 = 140 months, or about 11 years and 8 months. Break-even: about age 78 and 8 months.
67 vs. 70. By 70, the person claiming at 67 has collected $72,000. Waiting pays $480 more a month. $72,000 ÷ $480 = 150 months. Break-even: about 82 and a half.
62 vs. 70. Break-even is about 80 and 4 months.
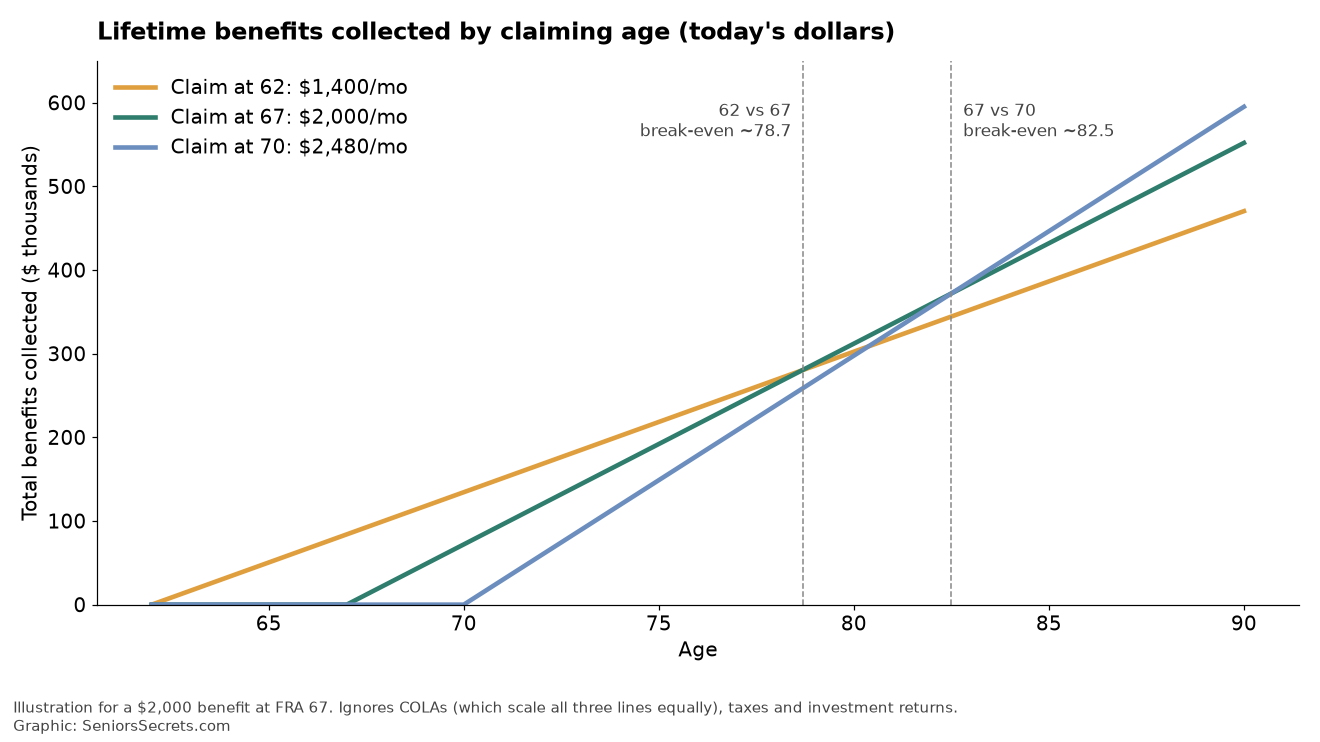
COLAs scale every claiming age equally, so they don’t shift these break-even ages much. What changes the picture is how long you live, taxes, and whether you’d draw down savings to delay.
A 65-year-old today has a good chance of reaching the mid-80s, and for married couples, the odds that at least one spouse lives into their 90s are high. That’s why delaying often pays off, especially for the higher earner in a couple.
Who should consider claiming early, and who should wait
Claiming earlier can make sense if:
- Your health or family history suggests a shorter-than-average life expectancy
- You’ve stopped working and have no other income to bridge the gap
- You’re the lower earner in a couple, and the higher earner is delaying
- You’re single and need the income now
Waiting usually pays off if:
- You’re healthy, and longevity runs in your family
- You’re the higher earner in a married couple (more on that below)
- You’re still working and earning well above the limit, since the earnings test would withhold much of an early benefit anyway
- You have savings to cover the gap
There’s a middle path too. Claiming at FRA avoids the reduction while skipping the wait to 70.
Spouses, survivors and divorced spouses
Your claiming age affects more than your own check.
- Spousal benefits max out at 50% of the worker’s PIA if the spouse claims at their own FRA. A spouse claiming at 62 gets 32.5% (with an FRA of 67). Spousal benefits earn no delayed credits, so there’s no gain in a spouse waiting past FRA. See Social Security spousal benefits.
- Survivor benefits are where delaying matters most. When one spouse dies, the survivor keeps the larger of the two checks. If the higher earner waited until 70, the survivor can inherit up to 100% of that bigger benefit, delayed credits included. See Social Security survivor benefits.
- Divorced spouses married at least 10 years can claim on an ex’s record under the same 50% rule, without affecting the ex’s benefit.
How to estimate your own benefit
You don’t need to do this math by hand.
- Create a my Social Security account. Your statement shows your estimated benefit at every age from 62 to 70, based on your actual earnings record.
- Check your earnings history on the statement. A missing year of earnings can lower your benefit, and you can ask SSA to correct it.
- Use SSA’s calculators for “what if” scenarios, such as stopping work early or earning more in your final years.
- Remember the 35-year rule. Benefits are based on your 35 highest-earning years, with zeros filling any gaps. Working a few more years can replace low or zero years.
When and how to apply
You can apply online, by phone at 1-800-772-1213, or at a local office up to four months before you want benefits to start. To start at FRA, aim for three months ahead.
If you’re past FRA when you apply, SSA can pay up to six months of benefits retroactively. But taking retroactive months reduces delayed credits, so it’s a tradeoff. My guide to retroactive benefits explains when that makes sense.
If you claim and regret it, you have two ways out. Within 12 months, you can withdraw your application by repaying everything you received. Or, at FRA, you can voluntarily suspend benefits to earn delayed credits until 70.

FAQ
What is my full retirement age if I was born in 1960?
- That applies to everyone born in 1960 or later. Born on January 1, 1960? SSA treats you as born in 1959, so your FRA is 66 and 10 months.
How much less do I get at 62?
With an FRA of 67, claiming at 62 cuts your benefit by 30%, permanently. You’d get 70% of your full benefit.
How much more do I get by waiting until 70?
8% for each year past full retirement age. With an FRA of 67, that’s 124% of your full benefit at 70.
What is the maximum Social Security benefit in 2026?
$5,181 a month for someone who starts at 70 in 2026 after 35 years of maximum taxable earnings. It’s $4,152 at full retirement age and $2,969 at 62.
Is full retirement age going to change again?
Proposals to raise it come up in Social Security reform debates, but no change has been enacted. Any increase would likely apply to younger workers, not people near retirement.
Related guides
2027 Social Security COLA Is 3.6%: What It Means for Your Check, SSI and Medicare
The $90 Medicare Part B Rebate: Who Gets It, When It Arrives, and What to Watch For
my Social Security Account in 2026: How to Sign In With Login.gov or ID.me, Fix Common Problems and Stay Safe