Medicare Late Enrollment Penalties and the General Enrollment Period: How the Math Works and How to Avoid It

Medicare’s late enrollment penalties are surcharges added to your premium if you don’t sign up when you’re first eligible and don’t have qualifying coverage. They aren’t one-time fees. For Part B and Part D, most people pay them for as long as they have that coverage.
If you’ve already missed your window, the General Enrollment Period, January 1 to March 31 each year, is your way back in. This guide covers how each penalty is calculated, the coverage that does and doesn’t protect you, and what to do if you think a penalty is a mistake.
I’m a researcher who reads Medicare’s rules closely. I’m not a licensed agent. The figures come from Medicare.gov and CMS, and I link to them. For free personal help, contact your State Health Insurance Assistance Program (SHIP).
The three penalties in one table
| Penalty | How it’s calculated | How long you pay | 2026 example |
|---|---|---|---|
| Part B | 10% of the standard premium for each full 12 months you could have had Part B but didn’t | For as long as you have Part B | 2 years late: $202.90 + $40.58 = $243.50 a month |
| Part D | 1% of the national base beneficiary premium for each full month without creditable drug coverage | For as long as you have Part D | 14 months: $38.99 × 14% = $5.50 a month |
| Part A (only if you buy Part A) | Premium goes up 10% | Twice the number of years you didn’t sign up | 2 years late: pay 10% more for 4 years |
The examples are Medicare.gov’s own, from its late enrollment penalty page. Most people get Part A without a premium, so the Part A penalty only affects people who have to buy it.
How the Part B penalty works
The Part B penalty is the expensive one. You pay an extra 10% of the standard premium for every full 12-month period you could have had Part B and didn’t, unless you qualified for a Special Enrollment Period.
Two details make it bigger than it looks:
- It’s tied to the current premium. The penalty is a percentage, so it grows each year the premium goes up. The 2026 premium is $202.90. The 2027 premium hadn’t been announced when I checked on October 1, 2026.
- It’s usually for life. You keep paying it for as long as you have Part B.
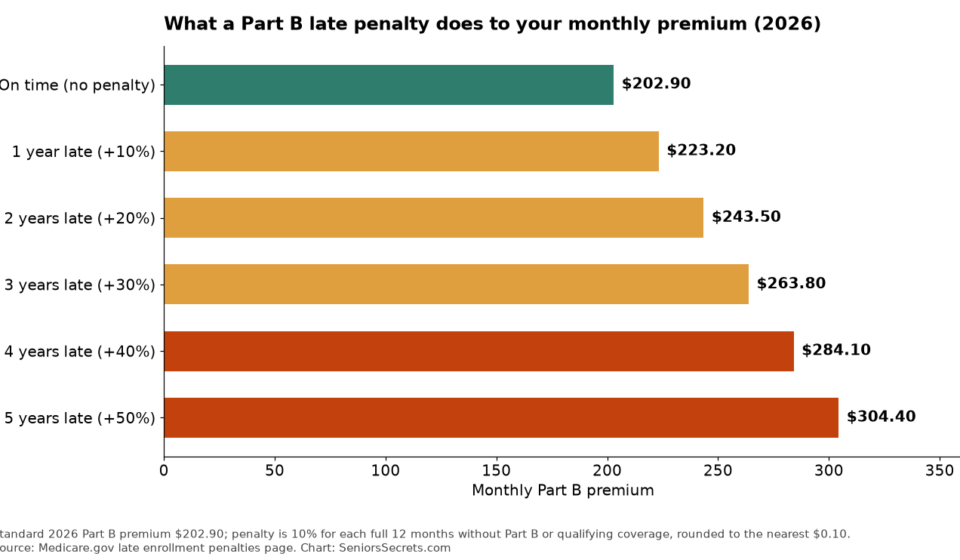
Here’s what that means in dollars at the 2026 premium:
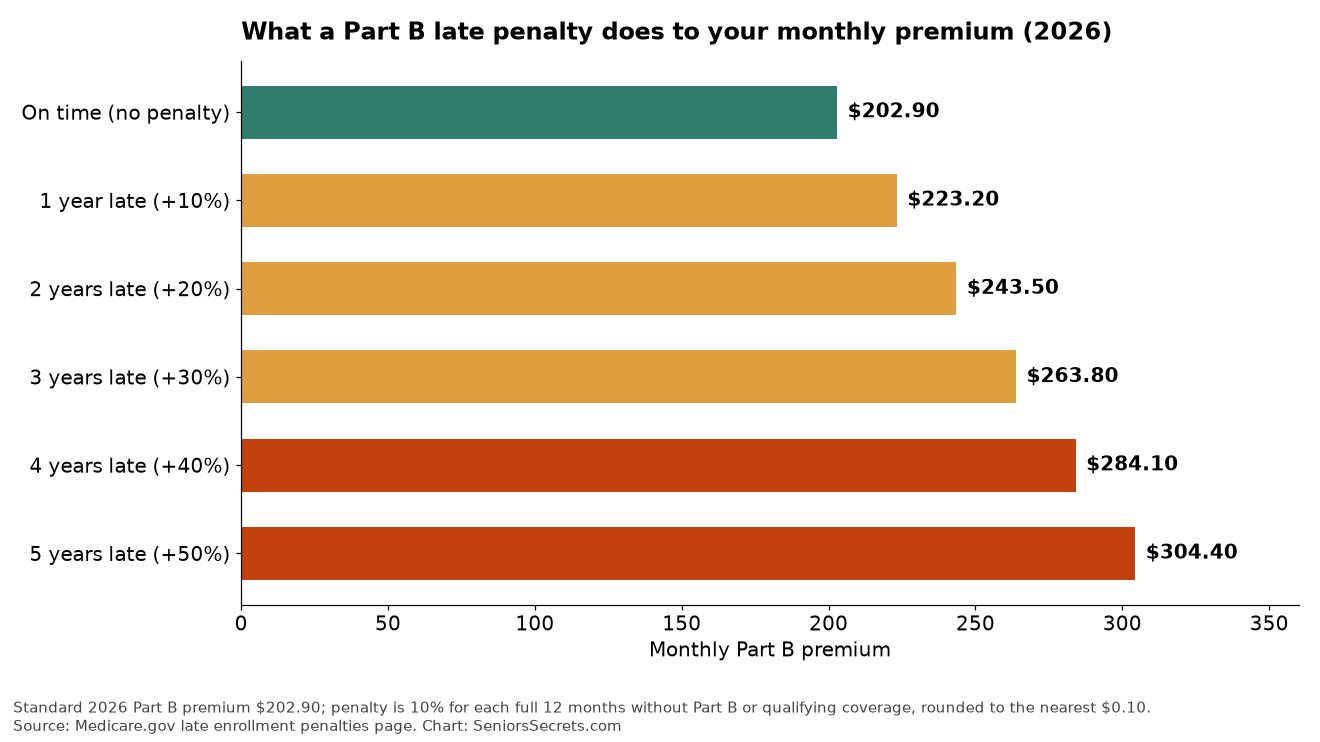
Five years late, the penalty adds about $101 a month, or roughly $1,200 a year, every year. Over 20 years in retirement, that’s more than $24,000 at today’s premium, and more as the premium rises.
How the Part D penalty works
The Part D penalty applies if you go 63 days or more in a row without Part D or other creditable drug coverage after your Initial Enrollment Period ends. It’s 1% of the “national base beneficiary premium” for each full month you went without coverage, rounded to the nearest 10 cents.
The base premium resets every year, so your penalty changes every year too. It’s $38.99 in 2026. CMS announced in July that it will be $41.33 in 2027. The same 14-month penalty from the table rises from $5.50 a month in 2026 to $5.80 in 2027.
The Part D penalty is small at first, but it builds. Someone who goes five years without drug coverage carries a 60% penalty, about $24.80 a month in 2027, on top of their plan premium, for as long as they have Part D.
If you qualify for Extra Help, you don’t pay a Part D penalty.
The General Enrollment Period: January 1 to March 31
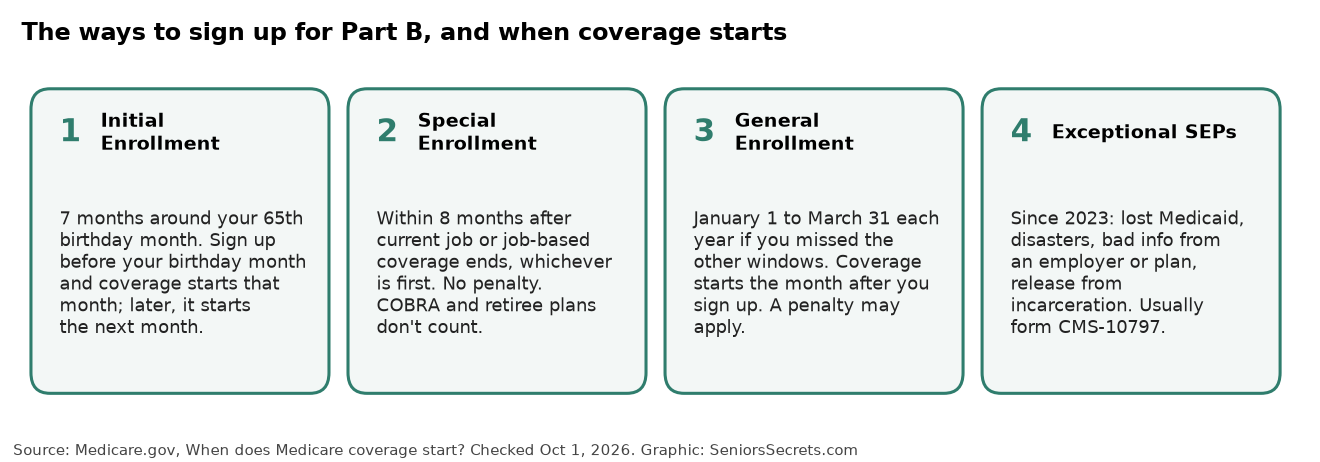
If you missed your Initial Enrollment Period and don’t qualify for a Special Enrollment Period, you can sign up for Part B (and premium Part A) during the General Enrollment Period, January 1 to March 31 each year.
Since 2023, your coverage starts the month after you sign up. That’s better than the old rule, which made everyone wait until July. Sign up in January and coverage starts February 1. Sign up on March 31 and it starts April 1.
You may owe a penalty, and the months between your Initial Enrollment Period and your sign-up count toward it. If you need Part B and you’re past your window, don’t wait for a “better” time. The penalty only grows.
Once your Part B starts, you can also join a Medicare Advantage or Part D drug plan. Ask about your enrollment window when you sign up, or check with your SHIP.
Coverage that protects you from the penalty, and coverage that doesn’t
This is where most expensive mistakes happen. People assume any health insurance lets them delay Part B. It doesn’t.
Protects you (Part B): health insurance from a job you or your spouse are currently working at. When that job or coverage ends, whichever is first, you have 8 months to sign up for Part B without a penalty. That’s the Special Enrollment Period, covered in detail in my guide to the Medicare Special Enrollment Period.
Doesn’t protect you (Part B): According to Medicare.gov’s coverage start page, these don’t give you a Special Enrollment Period:
- COBRA coverage. Getting COBRA doesn’t extend your 8-month window.
- Retiree health coverage.
- Marketplace (Obamacare) coverage.
Protects you (Part D): any drug coverage that’s “creditable,” meaning it’s expected to pay at least as much as standard Part D. Employer and union plans send a yearly notice saying whether their drug coverage is creditable. Keep those notices. They’re your proof if Medicare ever questions a gap.
The COBRA trap, step by step
Say you retire at 66 and take 18 months of COBRA from your old employer. Your 8-month Special Enrollment Period started when your job ended, not when COBRA ends. By the time COBRA runs out, the window closed 10 months earlier. You’d have to use the General Enrollment Period and you’d likely owe a Part B penalty.
The fix is simple if you know it: sign up for Part B within 8 months of leaving the job, even if you keep COBRA for a while.
New Special Enrollment Periods for exceptional situations
Since 2023, Medicare has offered Special Enrollment Periods for people who missed their window for reasons beyond their control. These include:
- Losing Medicaid coverage.
- Being affected by a declared natural disaster or emergency.
- Getting inaccurate or misleading information from your employer or health plan.
- Being released from incarceration.
- Other exceptional conditions, which you request directly from Social Security.
Most of these use form CMS-10797, sent to Social Security. If one of these applies to you, use it instead of the General Enrollment Period. You avoid both the wait and the penalty.
Can a penalty be removed?
Sometimes. Two common routes:
- Ask for a reconsideration. For Part D, your plan’s penalty letter explains how to ask an independent reviewer to reconsider, usually within 60 days. This works best when you had creditable coverage and can prove it. For Part B, contact Social Security if you think the months were counted wrong.
- Enroll in a Medicare Savings Program. If your income is limited, joining a Medicare Savings Program generally ends the Part B penalty, because the state pays your premium.
The paperwork matters in both cases. Keep your employer’s coverage letters, your creditable coverage notices and the dates your coverage started and ended.
A quick checklist before you turn 65 or retire
- Find your 7-month Initial Enrollment Period. It starts 3 months before the month you turn 65 and ends 3 months after it.
- If you’re still working, ask HR whether your plan counts as current employer coverage and whether its drug coverage is creditable. Get it in writing.
- If you’re leaving a job, sign up for Part B within 8 months, even if you choose COBRA.
- Don’t skip Part D just because you take no drugs. A low-premium plan costs less over time than a lifetime penalty.
- Keep every coverage letter in one folder.
For a plain-English rundown of what each part covers, see Medicare Part A vs Part B.
Special Enrollment Periods that can spare you the General Enrollment wait
The General Enrollment Period is the safety net when you missed your Initial Enrollment Period and don’t qualify for anything else. But several Special Enrollment Periods (SEPs) can let you enroll or switch without waiting for January–March — and without the late-enrollment penalty, when the trigger qualifies.
Per Medicare.gov enrollment periods and CMS notices checked October 12, 2026:
| Triggering event | What you can usually do | Typical window |
|---|---|---|
| Move out of a plan’s service area (or into an area with new options) | Switch Medicare Advantage or Part D | Month you move + 2 months |
| Lose employer, union, or retiree coverage | Enroll in Part B; join Advantage or Part D | Part B: up to 8 months; plan changes often shorter |
| Gain Medicaid, a Medicare Savings Program, or Extra Help | Join or change drug / Advantage coverage | Rules vary; Extra Help changes are often once per calendar quarter (Jan–Sep) |
| Your plan leaves Medicare or your area | Switch to another plan | Often Dec 8 through the last day of February |
| Move into or out of a nursing facility | Join, switch, or drop Advantage / Part D | While you’re there + 2 months after |
| Relied on wrong provider-directory info in Plan Finder (2026 only) | Switch Advantage plans or return to Original Medicare | First 3 months after a 2026 plan effective date — must call 1-800-MEDICARE |
The temporary 2026 Plan Finder provider-directory SEP
CMS added provider-directory information to Medicare Plan Finder. Because some listings can be wrong — especially early on — a temporary Special Election Period is available in 2026 if you:
- Enrolled in a Medicare Advantage plan through Plan Finder on Medicare.gov
- Have a plan effective date between January 1 and December 1, 2026
- Are within the first 3 months of that enrollment
- Found your preferred doctor is not actually in the plan’s network
You must call 1-800-MEDICARE (TTY 1-877-486-2048). Plans cannot process this SEP themselves. Call-center staff confirm the Plan Finder enrollment and help you switch to another Advantage plan, return to Original Medicare, or add Part D. The new coverage starts the first of the month after you apply. Keep a note of the date you checked Plan Finder and which doctor you expected to see.
Details: CMS fact sheet on the Plan Finder provider SEP (CMS Product No. 12231-P).
Three SEP mistakes that still cost people
- Assuming COBRA keeps the Part B clock paused. It doesn’t. Your Part B SEP after job-based coverage starts when employment or the group plan ends, not when COBRA runs out. The keeper sections above on the COBRA trap still apply.
- Waiting until a terminating plan formally drops you. The switch window for plans leaving Medicare often opens December 8, before January coverage ends.
- Letting a two-month window expire. Most plan-change SEPs close quietly. When in doubt, call your State Health Insurance Assistance Program (SHIP) or 1-800-MEDICARE the same week the event happens.
If none of these SEPs fit, the General Enrollment Period (January 1–March 31) and the penalty math earlier in this article are what you use.
FAQ
When is the Medicare General Enrollment Period?
January 1 to March 31 every year. Coverage starts the first day of the month after you sign up.
Will I always pay a penalty if I use the General Enrollment Period?
Not always, but usually. If you had no qualifying coverage for 12 months or more after your window closed, expect a Part B penalty.
Does COBRA let me delay Part B without a penalty?
No. COBRA isn’t treated as coverage from current employment, and it doesn’t extend the 8-month Special Enrollment Period.
How long do I pay the Part B penalty?
Usually for as long as you have Part B. The exception is people under 65 with Medicare due to disability, whose penalty ends when they turn 65 and get a new enrollment window.
Is there a penalty if I sign up for Part D late but had VA drug coverage?
VA drug coverage is generally considered creditable for Part D, so you shouldn’t owe a Part D penalty for that time. Keep your VA records to prove it.
Related guides